LTV and equity snapshot
What is a loan-to-value and home equity calculator?
A loan-to-value (LTV) and home equity calculator shows how much of your home's current value is still owed on the mortgage and how much you own outright. Lenders use LTV to decide refinance eligibility, interest rate pricing, private mortgage insurance (PMI) requirements, and how much you can borrow through a cash-out refinance or home equity line of credit (HELOC). Homeowners use it to check whether they can drop PMI, refinance, tap equity, or estimate what they would keep after selling.
LTV and equity snapshot
Uses appraised/market value today
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
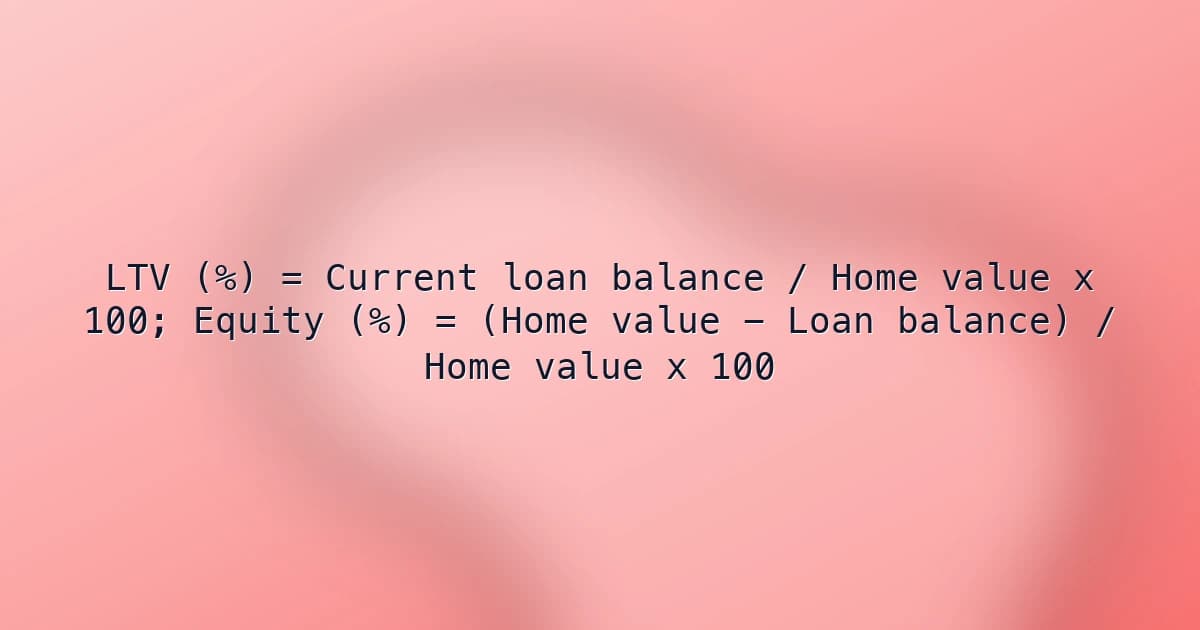
Loan-to-value and equity formula
LTV divides the mortgage balance by the home's value. Equity percentage is the remainder, so the two always add up to 100% while the loan balance is below the home's value.
LTV (%) = Current loan balance / Home value x 100; Equity (%) = (Home value - Loan balance) / Home value x 100- Equity in dollars = Home value - Loan balance.
- Combined LTV (CLTV) = (First mortgage + HELOC or second mortgage balances) / Home value x 100.
- Balance needed to reach a target LTV = Target LTV x Home value; for example, 80% of a $400,000 home is a $320,000 balance.
Inputs explained
LTV moves whenever either input changes, so use a current balance and a realistic value, especially before applying for a refinance, PMI removal, or HELOC.
- Current loan balance ($)
- Principal still owed from your latest mortgage statement or a payoff quote. For a combined LTV view, add any HELOC, home equity loan, or second mortgage balance secured by the same property.
- Home value ($)
- The property's current market value. Lenders use a formal appraisal or approved valuation model, which can differ from online estimates such as Zillow or Redfin. For pre-screening, use a conservative value based on recent comparable sales in your neighborhood.
Example loan-to-value calculation
A homeowner owes $318,000 on a home valued at $445,000. LTV is $318,000 / $445,000, about 71.46%, and equity is about 28.54%, or $127,000. If a lender allows borrowing up to 85% combined LTV, the homeowner could access roughly $60,250 through a HELOC ($445,000 x 85% - $318,000), or about $38,000 at an 80% limit, subject to credit and income approval.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the ltv and equity snapshot
- Input current loan balance ($) from your latest mortgage statement or payoff estimate to reflect principal outstanding accurately.
- Enter home value ($) using a recent appraisal or a conservative market-value estimate from comparable local sales.
- Review loan-to-value (LTV) to understand leverage level relative to current property value in percentage terms.
- Use the homeowner equity output to compare refinance, PMI, or equity-access scenarios under different value assumptions.
Common loan-to-value mistakes
- Using an online home value estimate when the lender's appraisal will decide the actual LTV.
- Leaving HELOC or second mortgage balances out when a lender will use combined LTV.
- Assuming PMI drops off automatically when current value rises, without requesting removal and meeting lender rules.
- Treating equity percentage as cash available to borrow, ignoring lender maximum LTV limits.
- Forgetting selling costs, which reduce the equity you actually keep when selling.
- Using the original loan amount instead of the current principal balance.
- Assuming FHA mortgage insurance ends at 80% LTV like conventional PMI.
Mortgage LTV planning context
- Conventional lending threshold context
- Many mortgage programs price and underwrite differently across LTV bands, with lower LTV generally associated with better terms and reduced risk pricing.
- PMI-related decision points
- Borrowers often monitor LTV levels because mortgage insurance requirements and cancellation pathways can depend on both balance and current property valuation.
- Appraised value sensitivity
- LTV can shift materially with appraisal outcomes, so conservative value assumptions are useful when pre-screening refinance or equity-access options.
FAQs
How much extra do I need to pay to get PMI removed on my conventional loan?
For a conventional loan in the US, you can generally request PMI cancellation once the balance reaches 80% of the home's original value, and it typically ends automatically at 78% on schedule. If your home was worth $400,000 at purchase and you owe $335,000 (83.75% LTV), the 80% target is a $320,000 balance, so about $15,000 in extra principal gets you there. Contact your servicer in writing, since requirements like payment history apply.
My home value went up a lot—can I use a new appraisal to drop PMI early?
Often yes, but rules are stricter than the 80% original-value threshold. Many conventional servicers require a new appraisal and an LTV around 75% if the loan is two to five years old, or 80% after five years, plus a clean payment history. On a $445,000 home, 75% LTV means owing no more than $333,750. Ask your servicer for its exact requirements before paying for an appraisal.
How much home equity can I actually borrow with a HELOC or cash-out refinance?
Multiply your home value by the lender's maximum combined LTV and subtract what you owe. On a $445,000 home with $318,000 owed, an 85% limit allows about $60,250 and an 80% limit about $38,000. Cash-out refinances on conventional loans are commonly capped around 80% LTV, while HELOC limits vary by lender, so your $127,000 of equity is not all borrowable.
I have a HELOC and a first mortgage—how do lenders calculate my LTV?
Lenders use combined loan-to-value, adding all loans secured by the home. With $318,000 on the first mortgage and $40,000 drawn on a HELOC, CLTV on a $445,000 home is about 80.45%, not 71.46%. Enter the combined balance in this calculator to see what a refinance or new lender will see, and note that some lenders count the full HELOC credit limit, not just the drawn amount.
My appraisal came in lower than expected—what does that do to my refinance?
A lower value raises LTV, which can raise your rate, trigger PMI, or reduce cash-out. If a $445,000 estimate appraises at $420,000, LTV on a $318,000 balance rises from 71.46% to about 75.71%. Options include requesting a reconsideration of value with better comparable sales, paying down principal to get below the next pricing threshold, or waiting for values to recover.
I have an FHA loan—will my mortgage insurance end when I reach 80% LTV?
Usually not the way conventional PMI does. For many FHA loans originated since mid-2013 with less than 10% down, mortgage insurance premiums last for the life of the loan; with 10% or more down, they typically end after 11 years. The common way out is refinancing into a conventional loan once LTV is at or below 80%, which this calculator can help you check.
Home values in my area dropped—am I underwater, and what can I do?
You are underwater when LTV is above 100%, meaning you owe more than the home is worth. A 10% drop on a $445,000 home to about $400,500 pushes LTV from 71.46% to 79.4%, still positive equity but closer to PMI and refinance thresholds. If you are underwater, keep making payments, avoid selling unless necessary, and ask your servicer about programs for borrowers with high LTVs.
How much equity will I actually walk away with if I sell my home?
Subtract selling costs, such as agent commissions, transfer taxes, closing costs, and repairs, from the sale price before subtracting the loan balance. With $445,000 value, $318,000 owed, and about 8% in selling costs, net proceeds are roughly $91,400, not the $127,000 shown as paper equity. Use a local cost estimate, since commissions and taxes vary by market.
What LTV do I need to get the best mortgage refinance rate?
Lower LTV generally gets better pricing. Conventional lenders typically adjust pricing in LTV bands, and staying at or below 80% avoids PMI. Dropping just under a band, such as from 80.5% to 79.9%, can change your rate or fees. Run this calculator with your expected appraisal and ask lenders where their pricing breaks fall.
Zillow says my home is worth more than my lender's appraisal—which value should I use?
For anything a lender decides, such as refinancing, PMI removal, or a HELOC, use the appraised value, because that is what underwriting uses. Online estimates rely on automated models and can miss renovations, condition, or unique features, in either direction. For planning, run this calculator with both values to see the range, and treat the lower one as your working assumption.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage planning & home equity analysisTopics: Loan-to-value, Home equity percentage, Refinance readiness
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine