Net operating income (NOI)
What is net operating income (NOI)?
Net operating income (NOI) is a rental property's annual income after vacancy, credit losses, and operating expenses, but before mortgage payments, capital expenditures, and income taxes. Start with gross scheduled rent, subtract vacancy and credit loss to get effective gross income (EGI), then subtract operating expenses. Landlords, real estate investors, brokers, and lenders use NOI to value properties with cap rates, check debt coverage, compare deals, and spot operating problems.
Net operating income (NOI)
Gross rent x (1 - vacancy) - expenses
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
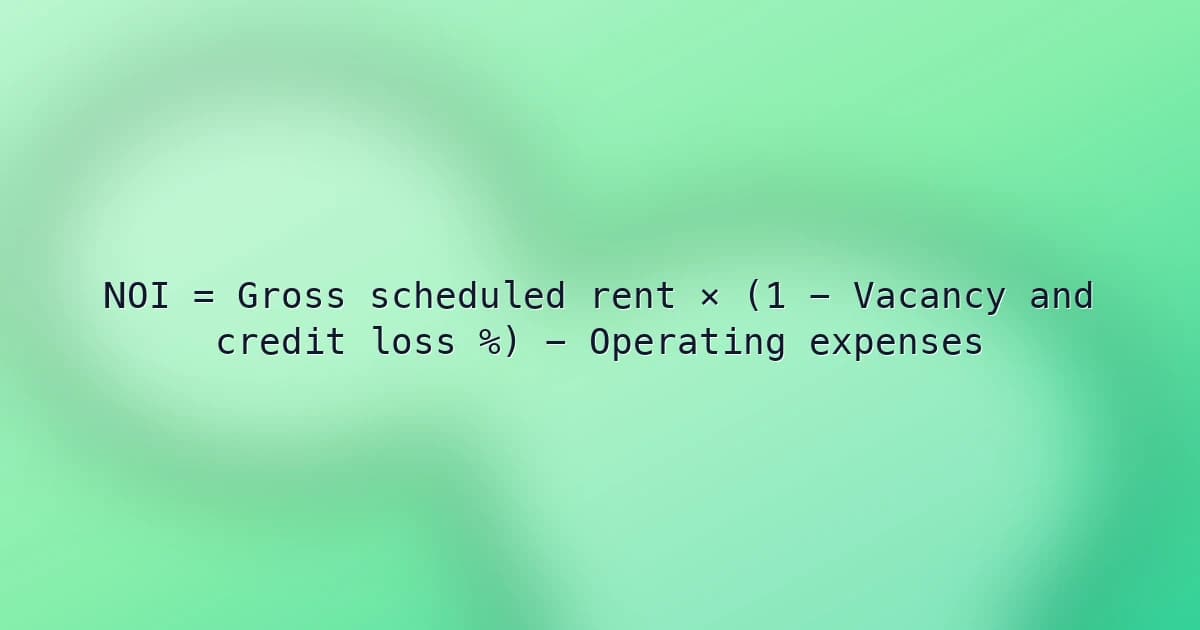
NOI formula
Reduce gross scheduled rent by the vacancy and credit loss rate, then subtract annual operating expenses.
NOI = Gross scheduled rent × (1 − Vacancy and credit loss %) − Operating expenses- Effective gross income (EGI) = Gross scheduled rent × (1 − Vacancy and credit loss %).
- Property value = NOI ÷ Cap rate. Debt service coverage ratio (DSCR) = NOI ÷ Annual debt service.
- Operating expense ratio = Operating expenses ÷ EGI × 100.
Inputs explained
Use actual rent rolls and trailing 12-month (T-12) operating statements where possible, and verify any seller-provided figures.
- Annual gross scheduled rent ($)
- Total annual rent if every unit were leased at current contract rents. Add other recurring income, such as parking or laundry, if you want it in NOI.
- Vacancy + credit loss (%)
- The share of scheduled rent you won't collect because of vacant units, unpaid rent, and concessions. Stabilized multifamily underwriting often uses about 5–8%, but base it on your property's history and market.
- Annual operating expenses ($)
- Property taxes, insurance, repairs and maintenance, utilities paid by the owner, payroll, property management, and administrative costs. Exclude mortgage payments, depreciation, income taxes, and major capital improvements.
Example NOI calculation
A 20-unit apartment building has $286,000 in gross scheduled rent, 6% vacancy and credit loss, and $118,000 in operating expenses. Effective gross income = $286,000 × 0.94 = $268,840. NOI = $268,840 − $118,000 = $150,840. That's an operating expense ratio of about 43.9%, and at a 6.5% cap rate, the property would be worth about $2.32 million.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the net operating income (noi)
- Input annual gross scheduled rent ($) from rent roll or GPR schedules aligned with contract rents, not aspirational market rents.
- Set vacancy plus credit loss (%) using T-12 collections and economic vacancy definitions consistent with your lender or investor memo.
- Input annual operating expenses ($) for property taxes, insurance, payroll, repairs, utilities, and management—exclude mortgage principal, interest, leasing commissions, and capital reserves unless your policy bundles them.
- Review estimated NOI and effective gross income; stress vacancy up and expenses higher before translating NOI into cap-rate value or debt coverage.
Common NOI mistakes
- Including mortgage payments in operating expenses.
- Using an unrealistically low vacancy rate or leaving out credit loss.
- Using a seller's pro forma that leaves out property management or reserves.
- Forgetting that property taxes can rise after a sale or reassessment.
- Using market rents instead of actual in-place rents.
Rent roll and NOI benchmarks
- Economic vacancy underwriting bands
- Stabilized multifamily portfolios often model roughly 5–8% economic vacancy plus credit loss unless trailing operations or lease-up prove tighter.
- Operating expense ratio (OER) guardrails
- Class B/C multifamily OER frequently clusters roughly 35–45% of effective gross income depending on payroll, utilities, and tax reassessment exposure.
- GPR versus collected rent
- Gross scheduled rent must reconcile to lease abstracts; concessions and bad debt belong in the vacancy and credit-loss line or a separate adjustment, not double-counted.
FAQs
The seller's NOI is much higher than mine—how much does it change the price?
A lot, because value is NOI divided by cap rate. If a seller uses 2% vacancy and leaves out about $21,500 in management, their NOI is $183,780 versus a realistic $150,840. That $32,940 gap is worth about $506,769 at a 6.5% cap rate. Rebuild NOI from the rent roll, T-12 statements, tax bills, and insurance quotes.
How much does a rise in vacancy reduce NOI and property value?
Raising vacancy from 6% to 10% on $286,000 of gross rent cuts effective gross income to $257,400 and NOI to $139,400, $11,440 less. At a 6.5% cap rate, that's about $176,000 less in property value. Stress-test higher vacancy before buying or refinancing.
My property taxes will be reassessed after purchase—how does that affect NOI?
Tax increases come straight out of NOI. If reassessment adds $12,000 a year, NOI falls from $150,840 to $138,840, which is about $184,615 less value at a 6.5% cap rate. Estimate taxes based on your purchase price and local rules, not the seller's current tax bill.
Will my NOI cover the mortgage payments?
Divide NOI by annual debt service to get DSCR. With $150,840 NOI and $115,000 in annual debt service, DSCR is about 1.31, leaving $35,840 in cash flow before taxes and reserves. Many lenders look for at least 1.20–1.25, so this NOI supports up to about $120,672 in annual debt service at 1.25.
What occupancy do I need to break even?
Divide operating expenses plus debt service by gross scheduled rent. With $118,000 in expenses, $115,000 in debt service, and $286,000 in gross rent, break-even occupancy is about 81.5%. Below that, rent won't cover expenses and the mortgage. A lower break-even point means less risk.
How much will a 5% rent increase raise my NOI?
If expenses stay the same, raising gross rent 5% to $300,300 increases NOI from $150,840 to $164,282, about $13,442 more a year at 6% vacancy. Higher rents can also raise turnover, so check market comps and renewal history before increasing.
Is my operating expense ratio too high?
Divide operating expenses by effective gross income. $118,000 ÷ $268,840 is about 43.9%. Older Class B and C multifamily properties often run about 35–45%, so this is within a typical range, though taxes, utilities, and payroll vary widely by market. Compare against similar local properties and your own history.
Should capital reserves be included in operating expenses?
It depends on who you're reporting to. Many lenders and appraisers deduct a replacement reserve, such as $300 per unit a year. For 20 units, that's $6,000, lowering NOI from $150,840 to $144,840. Be consistent and clear about whether reserves are included when comparing cap rates.
What's the difference between NOI and cash flow?
NOI is income after operating expenses but before mortgage payments, capital improvements, and income taxes. Cash flow subtracts those items too. With $150,840 NOI and $115,000 in debt service, cash flow before taxes and reserves is $35,840. Use NOI to value the property and cash flow to judge your return.
What is my property worth based on NOI?
Divide NOI by the market cap rate for similar properties. At $150,840 NOI, the property is worth about $2.32 million at a 6.5% cap rate. A lower cap rate means a higher value, so use cap rates from recent comparable sales in your area.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Income-property NOI modelingTopics: Effective gross income, Vacancy and credit loss, NOI underwriting
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine