Future nominal amount
What is an inflation future value calculator?
An inflation future value calculator converts an amount in today's dollars into the nominal dollars you would need in a future year to buy the same goods and services, assuming prices compound at a fixed annual inflation rate. It is used for retirement income targets, college savings goals, salary negotiations, long-term contracts, emergency fund sizing, and any plan where a goal stated in current dollars must be funded with future dollars that buy less.
Future nominal amount
Present sum × compound inflation
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
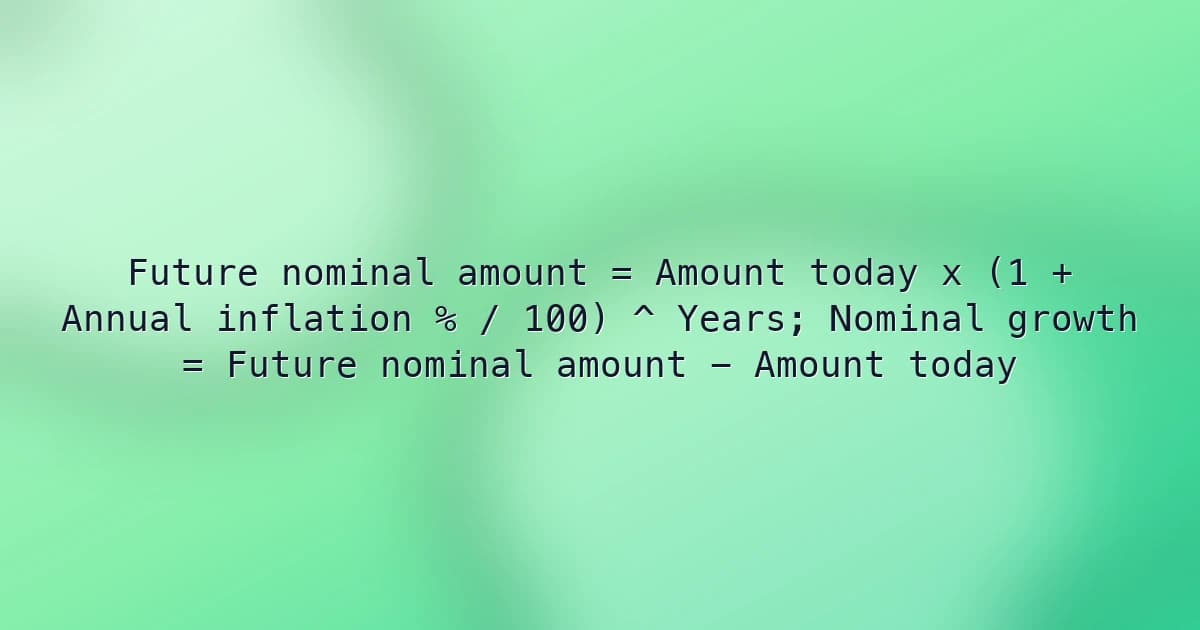
Inflation-adjusted future value formula
The calculator compounds today's amount by one plus the annual inflation rate, raised to the number of years ahead. The second output subtracts the original amount to show how much extra nominal money is needed just to stand still in purchasing power terms.
Future nominal amount = Amount today x (1 + Annual inflation % / 100) ^ Years; Nominal growth = Future nominal amount - Amount today- To go the other direction and find what a future amount is worth in today's dollars, divide by (1 + inflation rate) ^ years instead of multiplying.
- Rule of 72 shortcut: 72 divided by the inflation rate approximates the years it takes prices to double, about 22 years at 3.25%.
- A constant rate is a planning assumption, not a forecast; run low, base, and high scenarios rather than relying on a single number.
Inputs explained
Keep all three inputs on the same basis: a real, current-dollar goal, an inflation rate that matches what that goal actually costs, and a horizon that ends when the money is spent.
- Amount today ($)
- The cost of the goal in current prices, such as annual retirement spending, four years of tuition at today's sticker price, a home down payment, or a salary you want to preserve. Use what the goal costs now, not a nominal figure you already inflated elsewhere, or the calculator will compound inflation twice.
- Assumed annual inflation (%)
- The average yearly price increase you expect over the full horizon. Broad CPI-style assumptions often sit in the 2% to 3.5% range for long-run planning, while tuition, healthcare, and housing costs have historically run hotter, so match the rate to the spending category rather than defaulting to a headline number.
- Years ahead
- The number of years until the money is needed. For goals spent over many years, such as retirement or tuition, either run the calculator for each year of spending or use the midpoint of the spending window as a quick approximation.
Example inflation future value calculation
If a household wants $100,000 of today's purchasing power available in 15 years and assumes 3.25% annual inflation, the future nominal amount is $100,000 x 1.0325^15, about $161,566. That means roughly $61,566 of extra nominal funding is required just to preserve purchasing power. Viewed the other way, $100,000 saved in cash and left untouched for 15 years would buy only about $61,900 worth of goods in today's prices at that same inflation rate.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the future nominal amount
- Input amount today ($) as the current-dollar target you want to preserve in purchasing power terms.
- Set assumed annual inflation (%) to your planning scenario, using conservative and higher-stress cases for comparison.
- Enter years ahead to match the horizon of the goal, such as tuition timing or retirement start date.
- Review equivalent nominal sum later and nominal growth vs today to understand how much additional nominal funding your plan may require.
Common inflation planning mistakes
- Setting a savings target in today's dollars and never converting it to the nominal amount needed at the goal date.
- Using headline CPI for spending categories like tuition, healthcare, or rent that have historically inflated faster.
- Inflating a figure that was already quoted in future nominal dollars, which double counts inflation.
- Using the most recent year's inflation spike or dip as a 20- or 30-year average assumption.
- Comparing nominal investment returns to an inflation-adjusted goal without converting both to the same real or nominal basis.
- Treating a goal spent over many years as a single lump sum due at the start of the window.
- Running only one inflation scenario instead of stress-testing a higher-inflation case for long horizons.
Inflation planning context and assumptions
- Long-run inflation assumptions in planning models
- Many household and retirement plans use low-single-digit annual inflation assumptions, then stress-test higher scenarios for risk management.
- Short-term inflation volatility
- Observed CPI can move sharply year to year, so fixed-rate assumptions are useful for scenarios but should not be treated as forecasts.
- Nominal vs real values
- Nominal future amounts can rise substantially even when purchasing power is unchanged, which is why inflation translation is critical for long-horizon targets.
FAQs
How much will I need in retirement if I want to live on what $60,000 a year buys today?
Enter $60,000 as the amount today, your inflation assumption, and the years until retirement. At 3% over 25 years, you would need about $125,600 in the first year of retirement to match today's lifestyle. Spending keeps inflating during retirement too, so size your portfolio to the inflated first-year amount and keep raising withdrawals each year rather than freezing them.
What inflation rate should I use for a 20- or 30-year plan when recent inflation has been so volatile?
Avoid anchoring on the latest year. Use a long-run base case, commonly around 2.5% to 3% for broad prices, then run a stress case 1 to 2 points higher. Market-implied expectations, such as the gap between nominal and inflation-protected Treasury yields, offer a useful cross-check. If your plan only works at the low case, the plan is fragile.
How do I figure out what a future amount, like a $1 million retirement goal, is worth in today's dollars?
Reverse the calculation by dividing instead of multiplying: today's value = future amount / (1 + inflation) ^ years. At 3% over 30 years, $1 million buys roughly what $412,000 buys today. That gap is why a nominal savings milestone can feel large on paper while funding a much more modest lifestyle.
College tuition rises faster than CPI—how should I estimate the future cost of my child's degree?
Use a tuition-specific inflation rate rather than headline CPI, and price each year of attendance separately. For a child starting college in 15 years, inflate year one at 15 years, year two at 16, and so on, then add the four results. Using one lump sum at the start understates the total because later years inflate longer.
My salary went up 3% this year—did I actually get a raise after inflation?
Compare your raise to inflation over the same period. If prices rose 3.5% and pay rose 3%, your real income fell about 0.5%. Use this calculator to see what your current salary must become in future years to hold purchasing power, which gives a concrete number for negotiating cost-of-living adjustments.
How long until inflation cuts the value of my cash savings in half?
Use the Rule of 72: divide 72 by the inflation rate. At 3%, purchasing power halves in about 24 years; at 4%, about 18 years. Cash earning less than inflation loses real value every year, so emergency funds belong in high-yield savings and longer-term money needs assets expected to outpace inflation.
My investments are projected to return 7%—how do I tell if that actually beats inflation for my goal?
Compare on the same basis. Either inflate your goal with this calculator and compare it to nominal portfolio projections, or subtract inflation from returns to get an approximate real return and compare it to today's-dollar goals. A 7% nominal return with 3% inflation is roughly a 4% real return, which is the figure that actually grows purchasing power.
Why does my nominal future amount look so much bigger than expected even at a modest inflation rate?
Compounding applies each year's inflation to an already larger base. At 3.25% the cumulative increase is about 38% over 10 years but about 62% over 15 years and about 161% over 30 years. Small differences in the rate also matter: moving from 3% to 4% over 30 years raises the required nominal amount by roughly a third.
Should I inflate my whole budget at one rate, or use different rates for housing, healthcare, and everyday spending?
For high-stakes plans, split it. Run this calculator separately for categories that inflate at different speeds, such as healthcare and housing versus groceries and goods, then add the results. A single blended rate is fine for rough targets, but it can materially understate costs for retirees whose budgets skew toward healthcare.
I am signing a multi-year contract or lease with fixed pricing—how do I estimate how much value inflation will erode?
Enter the annual contract value as the amount today and the term in years. The nominal growth output shows how much more that same work or space would cost at market prices by the end of the term. Sellers use this to justify annual escalator clauses, and buyers use it to show the real discount a fixed price delivers in later years.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Personal finance & inflation planningTopics: Purchasing power, Inflation-adjusted budgeting, Future nominal value
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine