Present value of a future sum
What is present value?
Present value (PV) is what a future amount of money is worth today, given a discount rate that reflects your required return, opportunity cost, or risk. Because money available today can be invested, $250,000 received in seven years is worth less than $250,000 now. Investors, financial advisors, FP&A teams, and business owners use present value to compare lump-sum offers, value settlements and earnouts, price zero-coupon bonds, and decide how much to invest today to reach a future goal.
Present value of a future sum
PV = FV ÷ (1 + r)^n
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
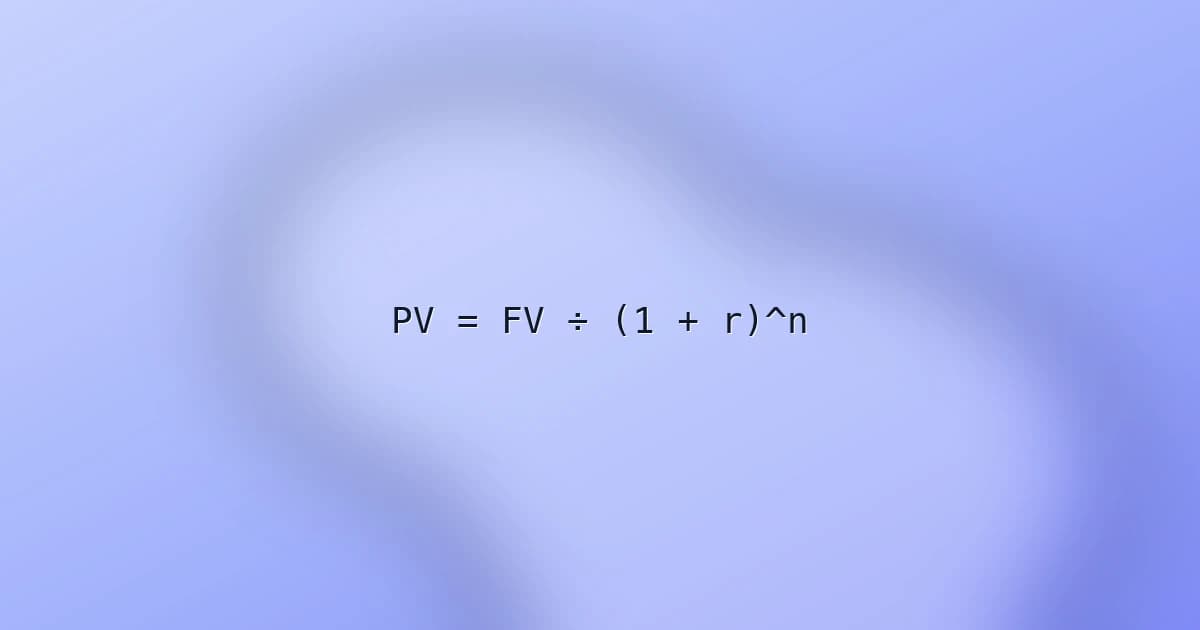
Present value formula
Divide the future amount by one plus the annual discount rate, raised to the number of years until you receive the money.
PV = FV ÷ (1 + r)^n- FV is the future amount, r is the annual discount rate as a decimal, and n is the number of years.
- Discount vs face value = FV − PV, the amount the future sum loses to time and required return.
- Implied discount rate of an offer = (FV ÷ PV)^(1 ÷ n) − 1. Use this to check what rate a buyer or lender is really applying.
Inputs explained
Present value is very sensitive to the discount rate and time horizon, so test several rates instead of relying on a single answer.
- Future amount ($)
- The single lump sum you expect to receive or pay at a future date, such as a settlement payment, a business earnout, a bond's face value, or a savings goal.
- Annual discount rate (%)
- The yearly return you require or could earn elsewhere. Lower-risk cash flows usually use lower rates, while uncertain payments, private deals, and business projects often use higher, risk-adjusted rates.
- Years until receipt
- The number of years from today until the money arrives. The longer the wait, the more the discount rate shrinks the present value.
Example present value calculation
You expect to receive $250,000 in 7 years and use a 9.5% discount rate. PV = $250,000 ÷ (1.095)^7 ≈ $132,446.71, a discount of about $117,553.29 from the face value. At a 7.5% rate, present value rises to about $150,689. At 11.5%, it falls to about $116,685—a $34,003 swing from a 4-point change in the discount rate.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the present value of a future sum
- Input future amount ($) as the single lump-sum cash inflow or outflow you want discounted at one point in time.
- Set annual discount rate (%) consistent with your assumptions on risk, inflation handling, and capital cost.
- Enter years until receipt as whole-year horizon from today to the modeled cash realization.
- Review present value today and discount versus face value, then rerun sensitivity cases across discount rates.
Common present value mistakes
- Using a discount rate that doesn't match the risk of the cash flow.
- Mixing nominal future amounts with inflation-adjusted (real) discount rates, or vice versa.
- Using this single-sum formula for recurring payments, which need annuity or cash-flow-by-cash-flow discounting.
- Ignoring taxes, fees, or the chance the payment never arrives.
- Relying on one discount rate instead of testing a range of rates.
Present value modeling context
- Discount rate selection practice
- Practitioners tie discount rates to opportunity cost of capital, project risk, or required returns; comparing scenarios across multiple rates is standard sensitivity practice.
- Nominal versus real cash flows
- Consistent modeling pairs nominal future amounts with nominal discount rates or pairs inflation-adjusted cash flows with real rates.
- Single-sum versus annuity distinctions
- This calculator handles one future lump sum; recurring cash flows require summing period-by-period PV components or annuity formulas.
FAQs
Should I take $100,000 today or $130,000 in 4 years?
Discount the $130,000 back to today and compare. At a 6% discount rate, its present value is about $102,972, slightly more than $100,000, so waiting wins. At 8%, it falls to about $95,554, so taking the money now is better. The break-even rate is about 6.8%, so it depends on what you could realistically earn and how certain the later payment is.
Is a structured settlement buyer's lump-sum offer fair?
Compare the offer with present value at a reasonable rate. A $50,000 payment due in 8 years is worth about $31,371 at 6%, but a buyer using a 12% rate would offer only about $20,194. Get quotes from several buyers, check the implied discount rate, and talk to a financial or legal professional before selling, since rules and court approval requirements vary by state.
How much do I need to invest today to have $100,000 in 15 years?
That's the present value of $100,000. Assuming a 6% annual return, you would need to invest about $41,727 today. A higher expected return lowers the amount needed but usually means more risk, so test conservative rates too.
What is $1 million in 30 years worth in today's dollars?
Discount it by expected inflation to see its purchasing power. At 3% annual inflation, $1,000,000 in 30 years buys about what $411,987 buys today. Use this for retirement goals so a target that sounds large isn't overstated in today's terms.
How do I value a business sale earnout paid in 3 years?
Discount the earnout at a rate that reflects the risk it won't be paid. A $500,000 earnout due in 3 years is worth about $328,758 today at a 15% risk-adjusted rate. If hitting the earnout targets is uncertain, also multiply by the probability of payment, and have a deal advisor review the terms.
How much should I pay for a property I expect to sell for $400,000 in 5 years?
Discount the expected sale price at your target return. At a 10% target, the present value is about $248,369, so paying more lowers your return unless the property also produces rental income. Add the present value of net rental income and subtract selling costs for a fuller valuation.
Someone offers me $80,000 now instead of $120,000 in 6 years—what rate are they using?
Solve for the implied discount rate: (120,000 ÷ 80,000)^(1 ÷ 6) − 1 ≈ 6.99% a year. If you could earn more than about 7% safely elsewhere, the $80,000 today may be the better choice. If the $120,000 is very secure and your alternatives earn less, waiting may be worth it.
Which is better: $60,000 in 2 years or $75,000 in 5 years?
Discount both to today at the same rate. At 8%, $60,000 in 2 years is worth about $51,440 and $75,000 in 5 years is worth about $51,044, so the earlier payment edges ahead. The break-even rate is about 7.7%: above it, the earlier payment wins, and below it, the later one wins. Also consider how reliable each payment is.
How do I price a zero-coupon bond with present value?
A zero-coupon bond pays only its face value at maturity, so its price is the present value of that amount. A $1,000 bond maturing in 10 years at a 4.5% yield is worth about $643.93 today. When market yields rise, the price falls, and longer maturities make the price more sensitive to rate changes.
Does monthly compounding change present value compared with annual discounting?
Yes. More frequent compounding means a slightly lower present value at the same stated rate. Discounting $250,000 over 7 years at 9.5% gives about $132,447 with annual compounding and about $128,905 with monthly compounding. This calculator uses annual discounting, so use an effective annual rate if your agreement compounds more often.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Corporate finance and valuation mathematicsTopics: Present value (PV), Discounted cash flow, Time value of money
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine