Illustrative demand range center
What is a personal injury settlement estimator?
A personal injury settlement estimator gives a rough, illustrative value for a claim from a car accident, slip and fall, workplace incident, or other injury by multiplying documented economic damages by a general-damages factor that stands in for pain and suffering. It mirrors the multiplier method often discussed in early demand-letter framing. It is a starting point for understanding how claims are commonly valued, not legal advice and not a prediction of what an insurer, jury, or court will pay.
Illustrative demand range center
Specials × general-damages factor — not legal advice
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
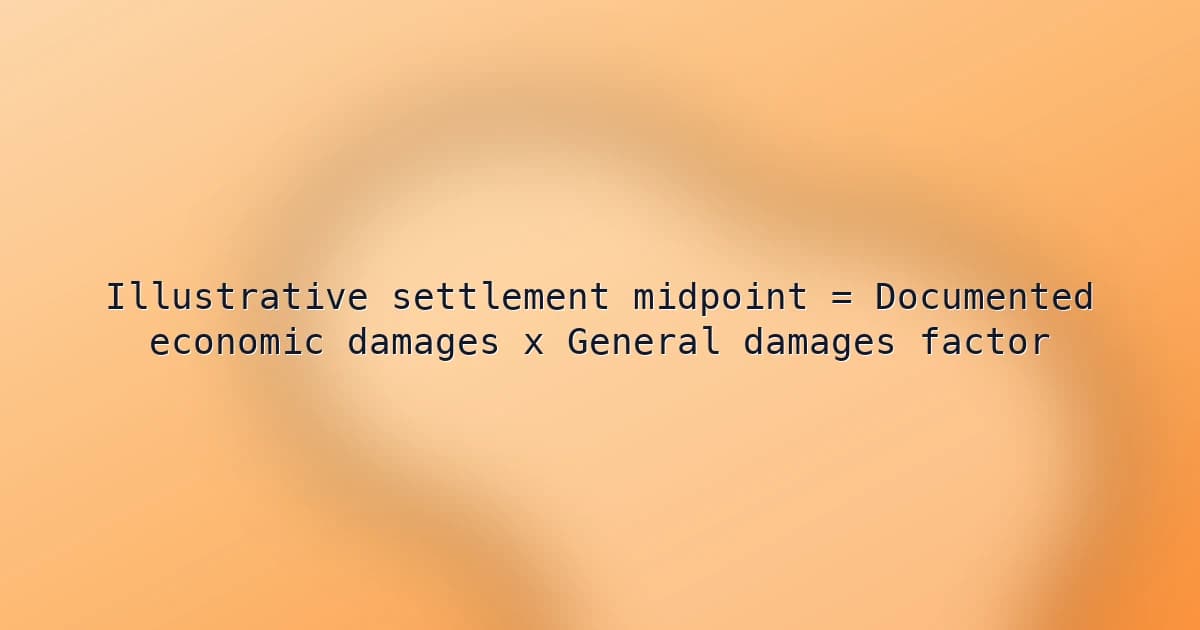
Injury settlement multiplier formula
The multiplier method adds up provable economic losses, often called special damages, and multiplies them by a factor that reflects injury severity, recovery time, and impact on daily life. The result approximates total damages before attorney fees, case costs, medical liens, fault reductions, and insurance limits.
Illustrative settlement midpoint = Documented economic damages x General damages factor- Economic damages typically include medical bills, future treatment supported by records, lost wages, lost earning capacity, and out-of-pocket costs.
- This calculator uses factors of 1.5 (conservative), 2.5 (moderate), and 4 (aggressive fact pattern); real negotiations may land outside these bands.
- Net to claimant = Gross settlement - attorney fees - case costs - medical liens and reimbursements, then adjusted for any comparative fault.
Inputs explained
The estimate is only as reliable as the records behind it, so enter amounts you can document with bills, statements, and receipts.
- Documented economic damages ($)
- Total provable losses from the injury: emergency care, hospital and surgery bills, physical therapy, prescriptions, medical equipment, wage-loss statements, and related out-of-pocket costs such as travel to appointments. Include future medical costs only when a treatment plan or medical opinion supports them. Whether billed amounts or amounts actually paid by insurance count can depend on state rules.
- General damages factor (case severity)
- A multiplier representing non-economic harm such as pain, emotional distress, and loss of enjoyment of life. Lower factors fit soft-tissue injuries that resolve within weeks; higher factors are usually reserved for fractures, surgery, permanent impairment, scarring, or long recovery with strong medical documentation and clear liability.
Example injury settlement calculation
A claimant with $48,000 in documented medical bills and lost wages using the conservative 1.5 factor gets an illustrative midpoint of $72,000. The moderate 2.5 factor produces $120,000, and the aggressive 4 factor produces $192,000. If the claimant were found 20% at fault, the conservative figure could fall to about $57,600 in a comparative-fault state, and from there attorney fees, case costs, and medical liens would come out before any money reaches the claimant.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the illustrative demand range center
- Input documented economic damages ($) from medical bills, wage-loss records, and receipts that can be supported by records.
- Select a general damages factor that reflects your scenario assumptions, understanding that this is a rough multiplier framework rather than a legal valuation method.
- Review the hypothetical midpoint output as a gross pre-deduction figure before fees, liens, comparative-fault adjustments, and policy-limit constraints.
- Compare conservative and higher-severity scenarios to frame discussion points, then seek licensed legal counsel for case-specific evaluation.
Common injury settlement estimate mistakes
- Treating the multiplier result as the amount the claimant will personally receive instead of a gross figure before fees and liens.
- Choosing the aggressive factor for soft-tissue injuries with short treatment and no objective findings.
- Including estimated future treatment that no doctor has documented or recommended.
- Ignoring the at-fault party's insurance policy limits, which can cap practical recovery.
- Forgetting health insurer, Medicare, Medicaid, or provider liens that must be repaid from the settlement.
- Overlooking comparative fault, which can reduce or, in some states, bar recovery.
- Settling before reaching maximum medical improvement, when future costs are still unknown.
- Missing the statute of limitations deadline while negotiating, which can eliminate the claim entirely.
Personal injury valuation context (illustrative, not legal advice)
- Multiplier approach in early case screening
- Some negotiators use economic-damages multipliers for rough framing, but final outcomes depend heavily on liability evidence, venue, and insurance limits.
- Policy limits and collectible recovery
- A modeled figure above available policy limits may not be recoverable, even where damages evidence is strong.
- Net-to-claimant vs gross settlement
- Claimants typically receive less than gross settlement after contingency fees, medical liens, case costs, and statutory deductions.
FAQs
The insurance company offered far less than this calculator shows—why, and what can I do about it?
Insurers often use claims software that discounts treatment it considers excessive, gaps in care, and injuries without objective findings, and first offers are commonly low to test whether you will accept. Gather complete medical records, itemized bills, wage documentation, and photos, and respond with a written demand explaining your damages. This calculator is illustrative only; a licensed personal injury attorney can tell you whether an offer is reasonable for your facts and jurisdiction.
My medical bills were $40,000 but health insurance paid only $15,000—which number should I use?
It depends on your state. Some jurisdictions let claimants present the full billed amount, while others limit recovery to amounts actually paid or owed. Because the multiplier applies to this figure, the choice can change the illustrative result dramatically, so run both numbers and ask an attorney which rule applies where the injury happened.
I was partly at fault for the accident—how much does that reduce my settlement?
In many comparative-fault states, recovery is reduced by your percentage of fault: at 20% fault, a $72,000 figure becomes about $57,600. Some states bar recovery if you are 50% or 51% or more at fault, and a few follow contributory negligence rules that can bar recovery for even minor fault. Apply your expected fault percentage to the calculator output and confirm the rule in your state.
My damages are higher than the at-fault driver's insurance policy limit—can I still recover the full amount?
Often not from that policy alone. Practical recovery may be capped at the liability limit unless other sources exist, such as your own underinsured motorist coverage, an umbrella policy, an employer's policy if the driver was working, or the defendant's personal assets. Ask for the at-fault party's policy limits early, since a calculator figure above available coverage may not be collectible.
How much will I actually take home after attorney fees, case costs, and medical liens?
Work from gross to net. On a $72,000 settlement with a one-third contingency fee ($24,000), $3,000 in case costs, and a $12,000 health insurance lien, about $33,000 would remain, before any fault reduction. Contingency percentages often rise if a case goes to litigation, and liens can sometimes be negotiated down, so ask your attorney for an estimated settlement statement before accepting an offer.
I waited three weeks to see a doctor after the accident—will that lower my settlement?
It can. Insurers commonly argue that gaps in treatment mean the injury was minor or caused by something else, which pushes valuations toward the conservative factor. Records explaining the delay, such as a scheduling backlog or symptoms that worsened over time, can help. Going forward, follow the treatment plan consistently and keep every appointment documented.
I am still in treatment—should I settle now or wait until I finish recovering?
Many attorneys recommend waiting until maximum medical improvement, the point where doctors can estimate future care, because once you sign a release you usually cannot reopen the claim for new costs. Balance that against the statute of limitations, which sets a hard deadline to file suit and varies by state and claim type. Never let negotiations run past that deadline.
How do I know whether my injury fits the 1.5x, 2.5x, or 4x multiplier?
Severity and evidence drive the factor. Soft-tissue sprains with a few months of therapy often sit at the low end. Fractures, injections, surgery, or months of documented limitations push toward the middle. Permanent impairment, scarring, or major lifestyle impact with clear liability may justify higher factors. Weak liability or inconsistent records pull every case down, regardless of injury type.
I am self-employed or a gig worker—how do I prove lost income for my injury claim?
Use tax returns, 1099s, platform earnings reports, invoices, bank deposits, and booking calendars showing work you had to cancel. Compare earnings before and after the injury over the same seasonal period, and get a doctor's note stating when you could not work. Documented lost income counts as economic damages and is multiplied in this model, so solid records matter more than estimates.
Is there another way to cross-check a multiplier estimate, like the per diem method?
Yes. The per diem method assigns a daily dollar amount for pain and suffering, often tied to daily earnings, and multiplies it by the days from injury to recovery. For example, $200 a day for 180 days is $36,000 in non-economic damages, added to economic losses. If per diem and multiplier results diverge widely, revisit your severity assumptions before using either figure in a discussion.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Personal injury claim valuationTopics: Settlement multiplier model, Special damages baseline, Demand range illustration
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine