Housing payment to income
What is a mortgage payment-to-income ratio?
The mortgage payment-to-income ratio, also called the front-end debt-to-income ratio or housing ratio, is the share of your gross monthly income that goes to your housing payment. Lenders use it with the back-end debt-to-income ratio to judge whether a mortgage is affordable, and many home buyers use the 28% guideline as a first check before pre-approval. This calculator divides your monthly housing payment by your gross monthly income and also shows how much gross income is left after housing.
Housing payment to income
Monthly housing payment ÷ gross monthly income × 100
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
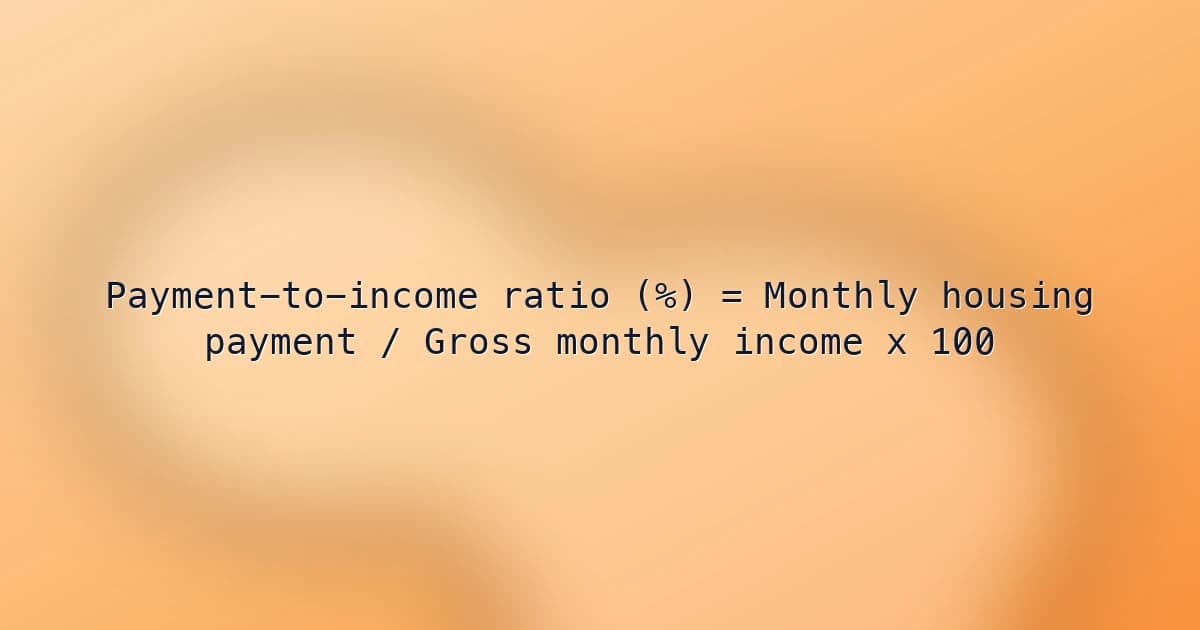
Payment-to-income ratio formula
The ratio compares one month of housing cost with one month of gross income, before taxes and deductions. Use the full housing payment, including taxes and insurance, for a result that is comparable to lender guidelines.
Payment-to-income ratio (%) = Monthly housing payment / Gross monthly income x 100- Gross income remaining after housing = Gross monthly income - Monthly housing payment.
- Maximum housing payment at a target ratio = Gross monthly income x Target ratio (for example x 0.28).
- Back-end DTI (%) = (Housing payment + Other monthly debt payments) / Gross monthly income x 100.
Inputs explained
Enter the same payment and income definitions a lender would use so your ratio lines up with real qualification guidelines.
- Monthly housing payment (P&I or PITI) ($)
- For lender-style results, enter the full payment: principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues. Principal and interest alone understates the ratio, sometimes by several percentage points.
- Gross monthly income ($)
- Income before taxes, retirement contributions, and health insurance deductions. Annual salary / 12, or hourly rate x hours x 52 / 12. For bonus, commission, or self-employment income, lenders commonly average about two years of documented income, so a single strong year may not fully count.
Example payment-to-income calculation
A borrower with a $2,680 monthly housing payment and $9,800 in gross monthly income has a payment-to-income ratio of $2,680 / $9,800 = about 27.35%, leaving $7,120 in gross income after housing. That is just under the 28% guideline, which would allow a payment of up to $2,744. With $650 in other monthly debt payments, back-end DTI would be about 33.98%, still under a common 36% guideline.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the housing payment to income
- Enter monthly housing payment using the same payment definition you use in planning (P&I only or full PITI/HOA).
- Input gross monthly income before taxes and deductions, aligned to how lenders typically evaluate qualifying income.
- Review payment-to-income (%) to see housing burden relative to income and check gross income remaining after housing payment.
- Run multiple scenarios with different payment assumptions or income levels to stress-test affordability before loan shopping.
Common payment-to-income ratio mistakes
- Using principal and interest only, then comparing the result with lender guidelines that assume the full housing payment.
- Entering take-home pay instead of gross income, which makes the ratio look worse than lenders will calculate it.
- Converting a biweekly paycheck to monthly by doubling it instead of multiplying by 26 / 12.
- Counting a one-time bonus or a single strong self-employed year as steady monthly income.
- Ignoring the back-end DTI, where car loans, student loans, and credit cards often cause denials.
- Treating a lender's maximum ratio as a comfortable budget without checking savings, childcare, and other real expenses.
Housing ratio underwriting context
- Front-end ratio guideline range
- Many underwriting frameworks assess housing-cost-to-income in the high-20% range, with allowable variance by loan program and borrower profile.
- Backend DTI interaction
- A strong housing-only ratio does not guarantee approval because lenders also evaluate total monthly debt obligations against income.
- Payment composition consistency
- Using consistent payment scope (P&I versus full PITI plus HOA) is essential when comparing ratio scenarios or lender thresholds.
FAQs
My housing ratio is 33%—how much do I need to lower my payment or loan to get to 28%?
Find the payment that hits 28%: gross monthly income x 0.28. At $9,800 a month, a $3,234 payment is 33%, and the 28% target is $2,744, so you need about $490 a month less. At 6.5% over 30 years, each $1,000 borrowed costs about $6.32 a month, so that means borrowing roughly $77,500 less through a cheaper home, a larger down payment, or a lower rate.
How much income do I need to qualify for a $2,680 monthly mortgage payment?
Divide the payment by your target ratio. At 28%, $2,680 / 0.28 = about $9,571 a month, or roughly $114,900 a year in gross income. Some loan programs allow higher housing ratios; FHA guidelines often reference 31%, which lowers the income needed to about $8,645 a month. Your other debts also have to fit under the back-end limit.
My housing ratio is under 28%, so why was my mortgage application still flagged?
Lenders also check back-end DTI, which adds car loans, student loans, credit card minimums, and other debt payments to the housing payment. A $2,680 payment on $9,800 income is 27.35% front-end, but with $1,000 in other debt the back-end ratio is about 37.55%. Credit score, cash reserves, employment history, and the appraisal also affect approval.
I get paid biweekly—how do I convert my paycheck to gross monthly income correctly?
Multiply the gross biweekly paycheck by 26, then divide by 12. A $4,000 biweekly paycheck is $8,666.67 a month, not $8,000. On a $2,680 payment, that difference changes the ratio from 33.50% to 30.92%. For weekly pay, multiply by 52 / 12; for hourly pay, multiply rate x hours x 52 / 12, so $45 an hour at 40 hours is $7,800 a month.
How do lenders count bonus or commission income in the housing ratio?
Lenders commonly average variable income over about two years and want to see it is likely to continue. With an $84,000 base salary and bonuses of $14,000 and $10,000, the averaged income is about $8,000 a month, putting a $2,680 payment at 33.50%. If the bonus cannot be documented, base pay alone is $7,000 a month and the ratio jumps to 38.29%, so run both scenarios.
I am self-employed—what income should I use to calculate my housing ratio?
Lenders typically use net business income after expenses from your tax returns, often averaged over two years, not gross revenue. If your returns show $118,000 and $98,000, the average is $9,000 a month, so a $2,680 payment is about 29.78%. Heavy write-offs lower qualifying income, so talk to a lender before filing if you plan to buy soon.
What does my housing ratio look like using take-home pay instead of gross income?
It will be noticeably higher, and it is a more realistic budget check. A $2,680 payment is 27.35% of $9,800 gross income, but if your take-home pay is $7,200, the same payment uses about 37.22% of what actually reaches your bank account. Use gross income for qualification and net income to judge whether the payment is comfortable.
Should I include property taxes, insurance, PMI, and HOA dues in the housing payment?
Yes, if you want to compare against lender guidelines, which are usually based on the full housing payment. A $2,212 principal and interest payment plus $400 in taxes, $150 in insurance, and $150 in PMI becomes $2,912; on $9,800 income, that raises the ratio from about 22.6% to about 29.7%. Property taxes in high-tax areas can easily push a buyer over 28%.
How do two incomes affect our housing ratio when buying a home with a partner?
Lenders combine the gross income of everyone on the loan, and also combine their debts. Incomes of $5,500 and $4,300 a month total $9,800, so a $2,680 payment is 27.35%. If one partner has $700 in student loan and car payments, the back-end DTI rises to about 34.49%. Also test whether one income could cover the payment if the other stopped.
What housing ratio is actually comfortable, not just the maximum I can qualify for?
Many planners suggest staying at or below about 25% to 28% of gross income, especially with childcare, high commuting costs, or irregular income. Qualifying at 31% or more may leave little room for savings, repairs, and emergencies. Run the calculator at 25%, 28%, and your lender's maximum, then compare each payment against your actual monthly budget.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage qualification and affordability analysisTopics: Front-end DTI, Housing payment ratio, Pre-approval planning
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine