Estimated payment savings
What is a mortgage refinance savings calculator?
A mortgage refinance savings calculator estimates how much you save each month and over the remaining life of your loan by replacing your current mortgage with a new one at a lower payment. Homeowners use it to decide whether refinancing is worth it when interest rates drop, and to compare refinance quotes before paying closing costs. Mortgage brokers and lenders use it to show borrowers the monthly and total payment difference alongside break-even math.
Estimated payment savings
(Old payment - new payment) x remaining months
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
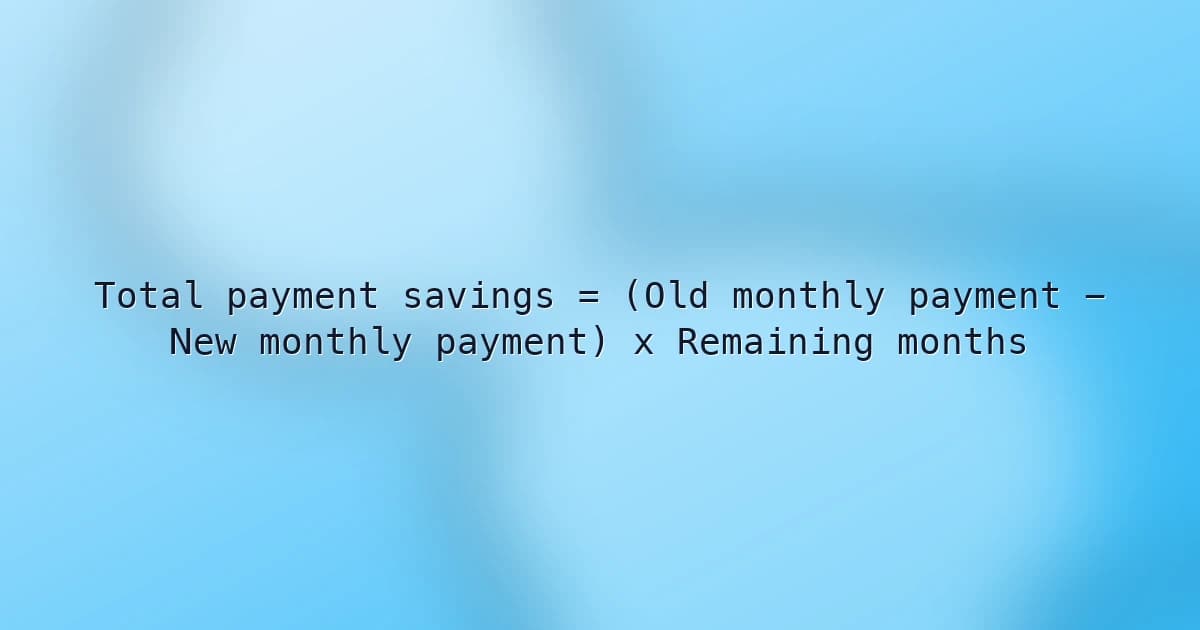
Refinance savings formula
The calculator multiplies the monthly payment difference by the number of months you expect to pay. It gives gross savings before closing costs, so pair it with a break-even calculation and make sure both loans cover the same number of months.
Total payment savings = (Old monthly payment - New monthly payment) x Remaining months- Monthly savings = Old monthly payment - New monthly payment.
- Break-even months = Refinance closing costs / Monthly savings.
- Net savings = Monthly savings x Months you keep the loan - Closing costs. If the new loan has a longer term, add the extra months of payments before comparing.
Inputs explained
Compare like with like: the same payment definition on both loans and a realistic number of months you will keep the new loan.
- Old monthly payment ($)
- Your current principal and interest payment from your mortgage statement. If you use the full payment with escrow, include escrow in the new payment as well. Include PMI on both sides if refinancing will remove it.
- New monthly payment ($)
- The principal and interest payment from the refinance loan estimate. Note the new loan term; a 30-year refinance has a lower payment partly because it stretches repayment over more years.
- Remaining months
- The months left on your current loan if the new loan keeps the same payoff date, or the number of months you realistically expect to keep the loan before selling or refinancing again. Overstating this number overstates savings.
Example refinance savings calculation
A homeowner owes about $335,400 at 7.5% with 280 months left, paying $2,540 a month in principal and interest. Refinancing to 6.25% over the same 280 months lowers the payment to about $2,280, saving $260 a month and $260 x 280 = $72,800 over the remaining term. With $6,000 in closing costs, break-even is about 23 months, and staying 5 years nets about $9,600.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the estimated payment savings
- Input old monthly payment ($) from your current loan statement for the same payment definition you use for the new quote (for example P&I only or full PITI).
- Input new monthly payment ($) from the refinance Loan Estimate for matching loan amount, term structure, and escrow assumptions.
- Set remaining months to the payoff horizon you want to evaluate (remaining amortization months if staying on schedule, or the months you realistically expect to hold the loan).
- Review monthly savings and total remaining payment difference, then layer closing costs and break-even math before committing to a refinance.
Common refinance savings mistakes
- Comparing a new 30-year payment with an old loan that has fewer years left, which hides the cost of the extra payments.
- Ignoring closing costs, or rolling them into the loan and forgetting that they increase the balance.
- Comparing a principal and interest payment with a full escrow payment.
- Counting an escrow refund or a 'skipped' payment as savings, when it is mostly your own money or prepaid interest.
- Refinancing shortly before selling, before monthly savings recover the closing costs.
- Looking only at the monthly payment instead of total interest and payoff date.
Refinance savings modeling context
- Closing cost recovery practice
- Lenders and borrowers typically compute break-even months by dividing upfront refinance costs by monthly payment savings to evaluate whether savings justify fees.
- Payment definition consistency
- Meaningful comparisons keep payment scope aligned across scenarios (for example P&I versus full PITI) so savings reflect apples-to-apples housing expense.
- Term and amortization interaction
- Lower monthly payments can sometimes accompany longer amortization or delayed equity buildup, so savings metrics should be paired with total interest and payoff timeline review.
FAQs
How much will I actually save from refinancing after closing costs?
Subtract closing costs from the monthly savings times the months you will keep the loan. Saving $260 a month with $6,000 in closing costs breaks even in about 23 months. Staying 5 years nets about $9,600 ($15,600 - $6,000), but selling after 18 months loses about $1,320. Use the months you realistically expect to stay, not the full loan term.
My refinance lowers my payment, but resets me to 30 years—am I really saving money?
Maybe not. On a $335,400 balance with 280 months left at 7.5%, a new 30-year loan at 6.25% drops the payment from $2,540 to about $2,065. That looks like about $133,000 in savings over 280 months, but you would make 80 extra payments. Total payments come to about $743,400 versus $711,200 on the old loan, about $32,200 more. Compare total payments over each loan's full term.
What if I refinance to a lower rate but keep paying my old payment amount?
You keep the low required payment for flexibility and still pay the loan off faster. Refinancing $335,400 to 6.25% for 30 years and continuing to pay $2,540 a month pays the loan off in about 225 months, or 18.8 years, instead of 280, saving roughly $142,000 in interest compared with the old loan. Confirm extra payments go to principal and that there is no prepayment penalty.
Is refinancing worth it if rates drop only 0.5%?
It depends on the loan balance, closing costs, and how long you stay. Dropping from 7.5% to 7.0% on $335,400 with 280 months left saves about $106 a month; with $6,000 in closing costs, break-even is about 57 months. The same costs with a 1.25% drop save $260 a month and break even in about 23 months. Larger balances make smaller rate drops worthwhile.
Should I roll closing costs into the new loan or pay them upfront?
Rolling costs in means no cash at closing, but a higher balance and smaller savings. Adding $6,000 to a $335,400 refinance at 6.25% over 280 months raises the payment to about $2,320, cutting monthly savings from $260 to about $220 and total savings from $72,800 to about $61,700. If you have the cash and plan to stay well past break-even, paying upfront usually saves more.
Should I refinance into a 15-year mortgage instead of a 30-year?
A 15-year refinance often has a lower rate and saves far more interest, but raises the payment. Refinancing $335,400 into a 15-year loan at 5.75% costs about $2,785 a month, about $245 more than the old $2,540, but cuts total interest from about $375,800 to about $165,900, saving roughly $209,900, and pays off the home about 8 years sooner. Make sure the higher payment fits your budget.
How do I calculate refinance savings on a cash-out refinance?
Payment savings are misleading with cash-out because the balance and often the term increase. Taking $40,000 cash out on $335,400 at 6.25% for 30 years gives a payment of about $2,311, still below $2,540, but you now owe $375,400 and pay for 80 more months. Treat the cash as new debt and compare its cost with alternatives such as a HELOC or personal loan.
Can refinancing to remove PMI change whether it is worth it?
Yes. Include PMI in the old payment if the refinance removes it. If you pay $2,540 plus $150 PMI and refinance to $2,280 with no PMI, monthly savings rise to $410 and $6,000 in closing costs breaks even in about 15 months. Conventional loans often allow PMI cancellation at about 80% loan-to-value without refinancing, so ask your servicer first; FHA mortgage insurance is often harder to remove.
Does the escrow refund or skipped payment after refinancing count as savings?
No. An escrow refund from the old loan is your own money returned, and the new escrow account usually needs to be funded at closing. A 'skipped' payment happens because interest is paid in arrears and prepaid interest is collected at closing, so it is not free money. Measure savings using the monthly payment difference and closing costs only.
Why is my total payment savings different from my interest savings?
They match only when the new loan keeps the same balance and payoff date. In the example, refinancing $335,400 from 7.5% to 6.25% over the same 280 months saves $72,800 in payments and about $73,100 in interest, nearly the same. If you extend the term, roll in costs, or take cash out, the payment difference no longer equals interest saved, so compare total interest on each loan.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage refinance cash-flow analysisTopics: Refinance payment savings, Mortgage interest economics, Loan comparison modeling
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine