Months to recover points cost
What is a mortgage points break-even calculator?
A mortgage points break-even calculator shows how many months it takes for the monthly savings from a lower interest rate to pay back the upfront cost of discount points. Home buyers and refinancing borrowers use it to decide whether buying down the rate is worth it, based on how long they expect to keep the loan. Lenders and mortgage brokers use it to explain rate sheet options and compare points with lender credits or a larger down payment.
Months to recover points cost
Points $ ÷ monthly P&I savings
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
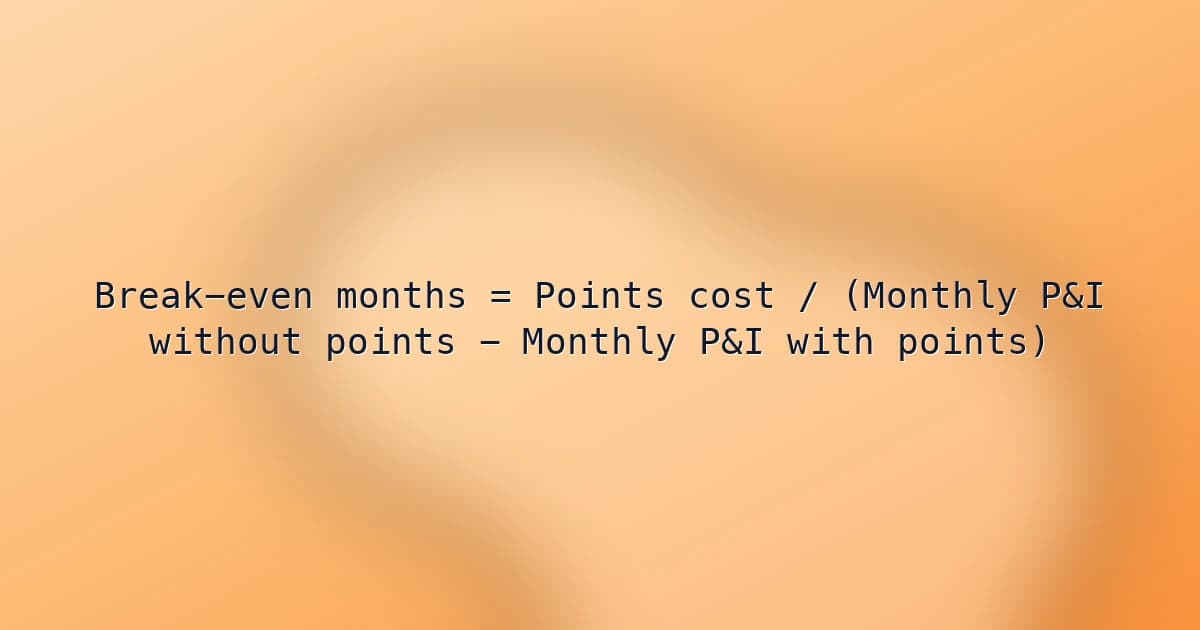
Mortgage points break-even formula
Break-even divides the upfront cost of points by the monthly principal and interest savings they create. If you keep the loan longer than the break-even period, the points save money; if you sell or refinance sooner, they cost money.
Break-even months = Points cost / (Monthly P&I without points - Monthly P&I with points)- Monthly savings = Monthly P&I without points - Monthly P&I with points.
- Net savings if you keep the loan = Monthly savings x Months kept - Points cost.
- Cost of one discount point is commonly 1% of the loan amount; how much it lowers the rate varies by lender and market.
Inputs explained
Use two loan estimates with the same loan amount, term, and loan type so the only difference is the rate and the points paid.
- Points / buydown cost ($)
- The total dollar cost of discount points shown on the loan estimate. Two points on a $370,000 loan cost about $7,400. Do not include standard closing costs that you would pay with or without points.
- Monthly P&I without points ($)
- The principal and interest payment at the no-points (par) rate. Leave out taxes and insurance, which do not change with points.
- Monthly P&I with points ($)
- The principal and interest payment at the lower rate you get by paying points, for the same loan amount and term. If the points are financed into the loan, use the payment on the higher loan balance.
Example mortgage points break-even calculation
A borrower pays $7,400 in discount points to lower the monthly principal and interest payment from $2,715 to $2,588, saving $127 a month. Break-even is $7,400 / $127 = about 58.27 months, or about 4.9 years. Keeping the loan for 7 years would net about $3,268 in savings, and keeping it for the full 30 years would net about $38,320. Selling or refinancing after 3 years would lose about $2,828.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the months to recover points cost
- Enter points/buydown cost ($) as the total upfront amount quoted to reduce the mortgage note rate.
- Input monthly P&I without points from the no-points loan quote for the same term and loan amount.
- Input monthly P&I with points from the rate-buydown quote so savings are measured on a like-for-like basis.
- Review monthly savings and break-even horizon, then compare against expected refinance or move timeline before choosing points.
Common mortgage points mistakes
- Paying points without an honest estimate of how long you will keep the loan before selling or refinancing.
- Comparing quotes with different loan amounts, terms, or loan types, which distorts the monthly savings.
- Ignoring the opportunity cost of the cash, which could go toward a down payment, reserves, or investments.
- Draining emergency savings to buy points and leaving no cushion for repairs after closing.
- Confusing permanent discount points with a temporary buydown that only lowers the payment for the first year or two.
- Assuming every lender gives the same rate reduction per point instead of comparing rate sheets.
Mortgage points decision context
- Discount point convention
- One discount point is commonly priced as 1% of loan amount, though rate improvement per point can vary by lender pricing and market conditions.
- Hold-period dependency
- Points are typically most favorable when expected loan hold time exceeds break-even months; shorter hold horizons reduce realized benefit.
- APR disclosure relevance
- Comparing APR alongside payment savings helps evaluate whether upfront points cost is justified relative to total borrowing cost.
FAQs
I might sell or move in about 3 years—should I still pay mortgage points?
Usually not, if the break-even is longer than your expected stay. With $7,400 in points saving $127 a month, three years of savings is only $4,572, so you would lose about $2,828. If you are unsure how long you will stay, compare a no-points loan or a loan with lender credits instead.
Rates might drop next year—does it make sense to buy points if I may refinance soon?
Refinancing ends the savings from your points, so the expected refinance date matters as much as a move. If you refinance after 30 months, you recover only about $3,810 of a $7,400 points cost. When rates look likely to fall, many borrowers skip points or pay fewer, and keep the cash for refinance closing costs.
Is it better to pay points or put the same money toward a bigger down payment?
Compare the payment reduction from each. On a $370,000 loan at about 8%, putting $7,400 more down lowers the payment by roughly $54 a month, while $7,400 in points that cut the rate to about 7.5% saves $127 a month. Points usually lower the payment more, but a bigger down payment builds equity and may help you reach 20% down to avoid PMI, which can tip the decision.
How does the opportunity cost of my cash change the points break-even?
Cash spent on points could earn a return elsewhere, which pushes the true break-even out further. If the $7,400 could earn about 4% a year, the monthly savings of $127 take about 65 months to catch up instead of 58. The higher your alternative return, or the more you need the cash for reserves, the less attractive points become.
Does the simple break-even ignore the faster principal paydown from a lower rate?
Yes. A lower rate means more of each payment reduces principal, so your balance falls faster too. On a $370,000 loan, counting the balance difference as well as the $127 monthly savings brings break-even to about 48 months instead of 58, with the lower-rate balance about $1,317 smaller by then. The simple formula is a conservative estimate.
What happens to the break-even if I roll the points into my loan amount?
Financing points increases your loan, so the monthly savings shrink. Adding $7,400 to a $370,000 loan at the 7.5% rate gives a payment of about $2,640, saving only about $75 a month versus $2,715, so it takes roughly 98 months for the savings to equal the added debt. Rolling in points mainly makes sense if you plan to keep the loan for a long time.
How do I know if the rate reduction per point is a good deal?
Run the break-even for each pricing option. If one point costs $3,700 and lowers the rate by 0.25%, from about 8% to 7.75%, on a $370,000 loan, the payment falls about $64 a month and break-even is about 57.6 months. Compare rate sheets from several lenders; options with break-even beyond 6 to 7 years are often hard to justify for buyers who may move or refinance.
Should I take lender credits instead of paying points?
Lender credits work in reverse: you accept a higher rate in exchange for money toward closing costs. Taking a $3,700 credit for a 0.25% higher rate on a $370,000 loan raises the payment about $65 a month, so you come out ahead if you sell or refinance within about 57 months. Credits suit short expected stays; points suit long ones.
Are mortgage points tax deductible, and does that change the break-even?
In the US, points paid on a purchase loan for a primary home may be deductible in the year paid if you itemize and meet IRS requirements, while refinance points are often deducted over the life of the loan. A deduction can shorten the effective break-even, but many households take the standard deduction and get no benefit. Confirm with a tax professional; this calculator uses payment savings only.
What is the difference between discount points and a 2-1 temporary buydown?
Discount points permanently lower the rate for the life of the loan, which is what this break-even calculation measures. A 2-1 temporary buydown lowers the payment for only the first two years, and the upfront cost roughly equals the payment subsidy, so there is no long-term break-even. Temporary buydowns are often seller-paid; permanent points make sense when you plan to keep the loan past break-even.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage pricing and rate buydown analysisTopics: Discount points break-even, Rate buydown economics, Mortgage cost comparison
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine