Months to recover closing costs
What is a refinance break-even point?
The refinance break-even point is the number of months it takes for your monthly mortgage savings to pay back the closing costs of a refinance. If a refinance costs $6,200 and lowers your principal and interest payment by $320 a month, you break even in about 19.4 months. Homeowners use the refinance break-even calculation to decide whether a lower mortgage rate is worth it, compare lender offers, and check whether they'll stay in the home long enough to come out ahead.
Months to recover closing costs
Closing costs ÷ monthly savings
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
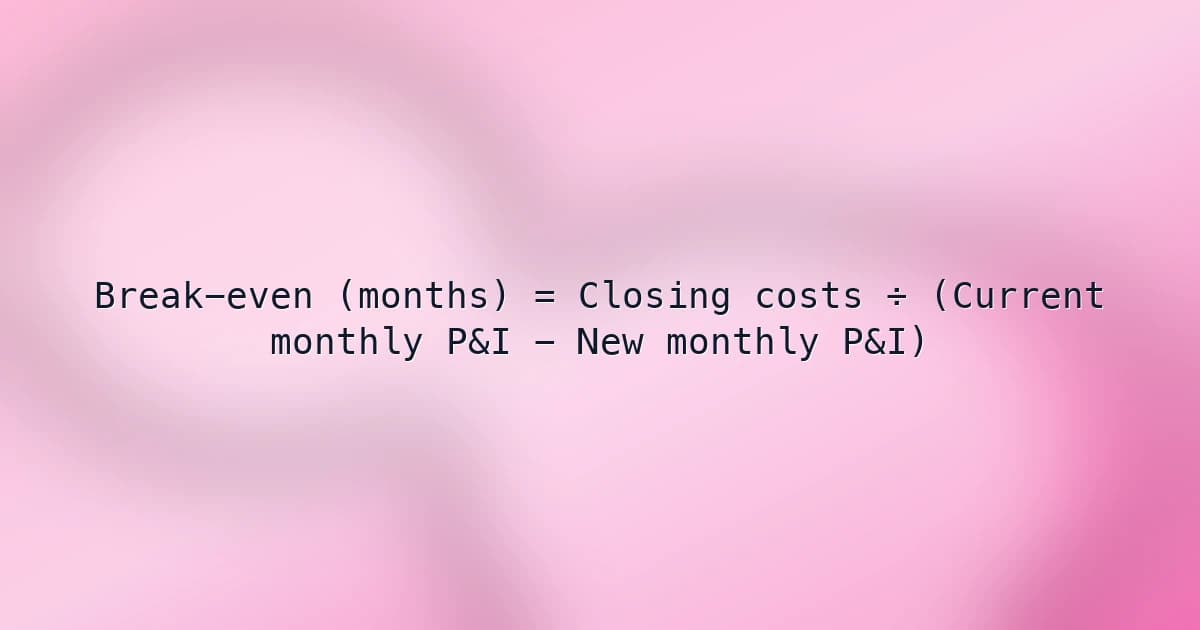
Refinance break-even formula
Divide total closing costs by your monthly principal and interest savings.
Break-even (months) = Closing costs ÷ (Current monthly P&I − New monthly P&I)- Monthly savings = Current P&I − New P&I.
- Net savings by a given month = (Monthly savings × Months) − Closing costs.
- Discount points break-even = Cost of points ÷ Extra monthly savings from the lower rate.
Inputs explained
Take closing costs and the new payment from the same lender Loan Estimate, and compare principal and interest only so changes in taxes or insurance don't distort the result.
- Closing costs + lender fees ($)
- All refinance costs you'll pay, including origination, appraisal, title, recording, and discount points, minus any lender credits. Prepaid interest and escrow deposits are usually treated separately.
- Current monthly P&I ($)
- The principal and interest portion of your current mortgage payment, not including property taxes, homeowners insurance, or mortgage insurance.
- New monthly P&I ($)
- The principal and interest payment on the new loan from your Loan Estimate. Make sure the loan amount includes any closing costs you plan to roll into the loan.
Example refinance break-even calculation
A homeowner with a $394,500 balance at about 6.89% pays $2,685 a month in principal and interest. Refinancing into a 30-year loan at 6.0% lowers P&I to about $2,365, saving $320 a month. With $6,200 in closing costs, break-even = $6,200 ÷ $320 ≈ 19.4 months. If they stay 5 years, net savings are about $13,000.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the months to recover closing costs
- Input total refinance closing costs and lender fees ($) from your Loan Estimate or Closing Disclosure line items you intend to pay net of lender credits.
- Input current monthly principal-and-interest ($) from your billing statement or amortization schedule for the existing loan.
- Input new monthly P&I ($) from the lender’s LE using the same remaining balance and term assumptions you are actually approving.
- Read months to recover closing costs and monthly savings; repeat with conservative quotes if discount points, MI, or escrow reserves shift the fully loaded payment.
Common refinance break-even mistakes
- Comparing total monthly payments that include escrow changes instead of principal and interest only.
- Ignoring the extra years of payments when refinancing into a new 30-year loan.
- Rolling closing costs into the loan and assuming the refinance is free.
- Forgetting discount points or lender credits when entering closing costs.
- Refinancing when you plan to sell or move before the break-even point.
Refinance payback context
- Typical refinance settlement costs
- Industry guidance often cites roughly 2–5% of loan amount for refinance closing costs including lender, title, and recording fees, though fixed-dollar quotes are common on smaller balances.
- Mortgage tenure vs break-even
- National median homeowner tenure has often landed near 12–13 years in Census/HUD discussions, but mobility varies by market; compare break-even months to your planned hold period.
- Rate quote validity
- Retail rate locks commonly run 30–60 days; if closing slips, repricing can change P&I and the implied break-even unless you re-run the math.
FAQs
I might sell my house in 3 years—is refinancing still worth it?
Compare savings over the time you'll stay with the closing costs. Saving $320 a month for 36 months is $11,520, so after $6,200 in costs you'd net about $5,320. But if you sell after 15 months, you'd save only $4,800 and lose about $1,400. Refinance only if you're fairly confident you'll stay past the break-even point.
Should I roll closing costs into the new loan instead of paying cash?
It avoids cash at closing, but you'll pay interest on the costs. Adding $6,200 to a $394,500 loan at 6% raises P&I from about $2,365 to $2,402, so monthly savings drop from $320 to about $283. The refinance isn't free—you're borrowing the closing costs, which also reduces your home equity.
Should I pay discount points to get a lower refinance rate?
Calculate a separate break-even for the points. Paying 1 point ($3,945 on $394,500) to cut the rate from 6.0% to 5.75% lowers P&I by about $63 a month, so the points take about 63 months, over 5 years, to pay back. Points make sense mainly if you'll keep the loan well past that.
Is a no-closing-cost refinance better than paying closing costs?
It depends on how long you'll keep the loan. If the lender covers costs in exchange for a 6.375% rate instead of 6.0%, P&I is about $2,461, saving $224 a month instead of $320, but you break even immediately. The paid option saves about $96 more each month, so it takes about 65 months ($6,200 ÷ $96) to come out ahead. If you might sell or refinance again within about 5 years, the no-cost option usually wins.
Am I really saving money if I refinance into a new 30-year loan?
Check total remaining payments, not just the monthly amount. With 27 years left at $2,685, you'd pay about $869,940 more. A new 30-year loan at $2,365 totals about $851,400, around $18,540 less before closing costs, but over 3 extra years. To keep your payoff date, pay the old amount or choose a shorter term.
How does removing PMI change my refinance break-even?
Add the mortgage insurance you'll eliminate to your monthly savings. If refinancing also removes $150 a month of private mortgage insurance, total savings are $470, and break-even drops from 19.4 months to about 13.2 months. Confirm your home's appraised value and equity qualify to remove mortgage insurance.
Does break-even work for a refinance to a 15-year mortgage?
Not on its own. A 15-year refinance often raises the payment: $394,500 at 5.5% for 15 years is about $3,223 a month, more than the current $2,685, so there's no monthly savings to divide into closing costs. Compare total interest paid and your payoff date instead, and make sure the higher payment fits your budget.
How much does my mortgage rate need to drop for a refinance to make sense?
There's no single rule. A smaller rate drop can still work if the loan is large and closing costs are low. A drop from about 6.89% to 6.0% on $394,500 saves $320 a month and breaks even in about 19 months. Run your own numbers with real Loan Estimates and compare the break-even to how long you'll stay.
How much will I save over 5 years after refinancing?
Multiply monthly savings by months, then subtract closing costs. $320 a month for 60 months is $19,200, minus $6,200 in costs, for about $13,000 in net payment savings. That doesn't include interest savings or the effect of restarting your loan term, so compare total interest too.
Why does my lender's break-even estimate differ from this calculator?
Lenders may include escrow changes, prepaid interest, or skipped payments in their numbers, which can make the refinance look better. Use principal and interest only and include all fees and points, minus lender credits, for a true comparison. Compare Loan Estimates from multiple lenders on the same day.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage refinance analysisTopics: Refinance break-even, Closing cost recovery, P&I payment savings
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine