Net after card fees
What is a payment processing fee calculator?
A payment processing fee calculator shows how much a credit card or online payment processor, such as Stripe, PayPal, Square, or a merchant account, takes from each transaction, and how much you actually receive. It combines the percentage fee and fixed per-transaction fee to calculate your net deposit and effective fee rate. Small businesses, freelancers, ecommerce stores, and finance teams use it to price products, invoice clients, and compare payment options.
Net after card fees
Percent fee + fixed authorization fee
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
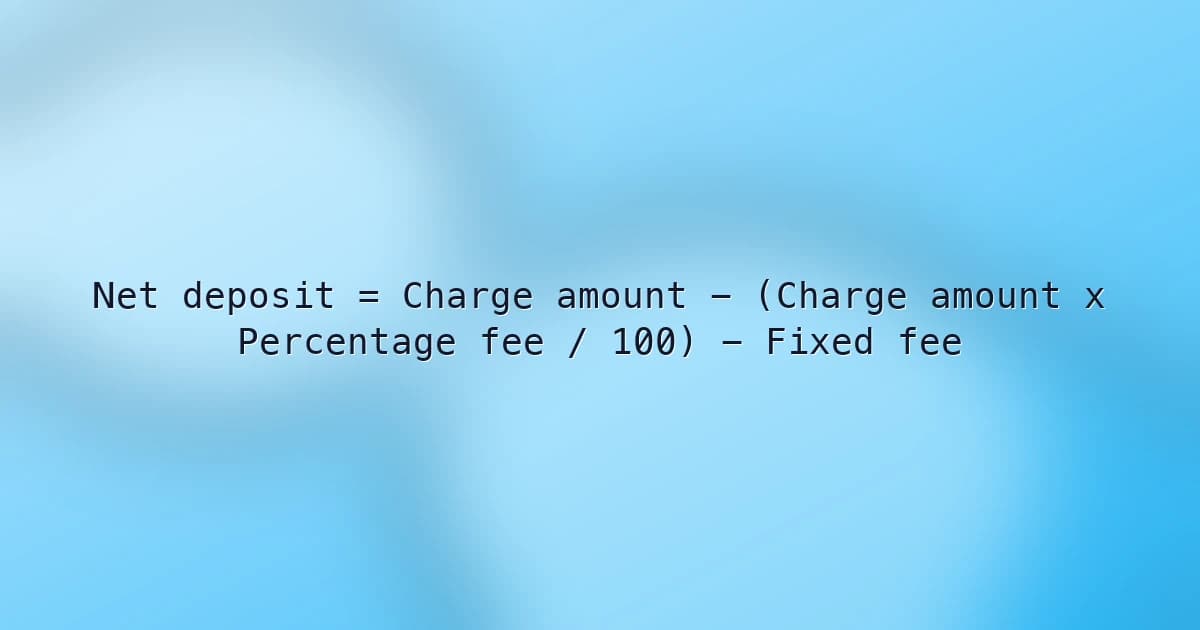
Payment processing fee formula
Processing fees usually combine a percentage of the charge and a fixed fee per transaction. Subtract both from the charge to get your net deposit.
Net deposit = Charge amount - (Charge amount x Percentage fee / 100) - Fixed fee- Total fee = Charge amount x Percentage fee / 100 + Fixed fee.
- Effective fee rate (%) = Total fee / Charge amount x 100.
- Amount to charge to receive a target net = (Target net + Fixed fee) / (1 - Percentage fee / 100).
Inputs explained
Use the rates from your processor's pricing page or your latest statement for the type of payment you are modeling.
- Charge amount ($)
- The amount charged to the customer for one transaction, or your average order value if you are modeling typical fees.
- Percentage fee (%)
- The processor's percentage rate, such as 2.9% for many online card payments. International cards, currency conversion, manual entry, and certain card types can add extra percentage fees, so include them if they apply.
- Fixed fee per charge ($)
- The flat fee per transaction, such as $0.30 for many online processors. This fixed fee has a much bigger impact on small transactions than on large ones.
Example payment processing fee calculation
A $2,500 invoice paid by card at 2.9% + $0.30 costs $72.50 + $0.30 = $72.80 in fees, so the business receives $2,427.20. The effective fee rate is about 2.912%. To receive the full $2,500 after fees, you would need to charge about $2,574.97.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the net after card fees
- Input charge amount ($) for a single capture or the average ticket you want to model for fee drag.
- Set percentage fee (%) and fixed fee per charge ($) from your processor rate card or recent settlement statement line items.
- Review estimated net deposit and blended fee as percent of charge to see how fixed cents change effective rate on small tickets.
- Run scenarios for higher-ticket and lower-ticket orders to stress-test margin after processing before setting posted prices.
Common payment processing fee mistakes
- Ignoring the fixed fee, which makes small transactions much more expensive than the headline rate.
- Adding the percentage fee to the price to cover fees, which falls slightly short; you need to gross up instead.
- Forgetting international card and currency conversion fees for overseas customers.
- Assuming refunds return the processing fee, when many processors keep it.
- Adding a credit card surcharge without checking card network rules and local laws.
- Never comparing flat-rate pricing with interchange-plus pricing as volume grows.
Card acceptance fee context
- Interchange-plus versus flat pricing
- Many businesses pay interchange and network assessments plus processor markup, while others use flat blended rates; net deposit math should mirror the contract you actually sign.
- Card-present versus not-present risk
- Card-not-present transactions generally carry higher processing risk and may price above in-person tap or dip transactions under card network rules.
- Surcharge and compliance constraints
- Passing fees to cardholders is regulated by card brand rules and local law, so pass-through policies require legal and scheme compliance review.
FAQs
How much should I charge so I receive the full amount after Stripe or PayPal fees?
Gross up the price: (Target amount + Fixed fee) / (1 - Percentage fee). To receive $2,500 at 2.9% + $0.30, charge about $2,574.97. Simply adding 2.9% ($2,572.50) leaves you about $2.40 short, because the fee also applies to the added amount. Check that passing fees to customers is allowed by your processor and local rules.
Why are processing fees so high on my small transactions?
The fixed fee takes a bigger share of small payments. At 2.9% + $0.30, the effective rate is about 8.9% on a $5 sale, 5.9% on $10, 4.4% on $20, and 3.2% on $100. Coffee shops and low-ticket businesses can reduce this with minimum card amounts where allowed, bundling purchases, or micropayment pricing plans.
How much do processing fees cost my business per month and per year?
Multiply transactions by the fee per transaction. With 800 transactions a month averaging $50, fees are $1.75 each, or $1,400 a month on $40,000 in sales, an effective rate of 3.5%. That is $16,800 a year, so even small rate improvements are worth negotiating.
Do I get processing fees back when I refund a customer?
Often not. Many processors keep the original processing fee when you issue a refund, so refunding a $2,500 payment can still cost you the $72.80 fee. Check your processor's current refund policy, and factor refund-related fee losses into your pricing and return policy.
How much extra do international payments cost in processing fees?
International cards and currency conversion often add percentage fees on top of the standard rate. If a $2,500 payment incurs an extra 1.5% international fee and 1% currency conversion fee, the total rate is 5.4% + $0.30, about $135.30 instead of $72.80. Check your processor's pricing for international and currency fees.
Is ACH or bank transfer cheaper than card payments for large invoices?
Usually, yes. If ACH costs 0.8% capped at $5, a $2,500 invoice costs $5 instead of $72.80 by card, saving about $67.80. For B2B invoices and large payments, offering ACH or bank transfer as the default option can cut fees significantly, although it takes longer to settle.
Can I add a credit card surcharge to cover processing fees?
Sometimes, with restrictions. Card network rules commonly cap surcharges at a few percent and require disclosure, some US states and countries restrict or ban surcharging, and debit cards usually cannot be surcharged. Cash discounts or building fees into prices are alternatives. Check current card brand rules and local law before adding a surcharge.
Should I switch from flat-rate to interchange-plus pricing?
Compare your effective rate under each. If your flat 2.9% + $0.30 works out to about 3.5% on $40,000 a month, and an interchange-plus quote averages about 2.4% plus monthly fees, the percentage savings could be several hundred dollars a month. Interchange-plus usually becomes attractive at higher volumes and larger tickets; include any monthly or statement fees in the comparison.
How do I price products to cover payment processing fees?
Gross up your target revenue per item. To keep $50 after 2.9% + $0.30, the price needs to be about $51.80. Many businesses instead build an average fee of about 3% into their margins across all products rather than adjusting each price.
Are processing fees tax deductible for my business?
In many countries, including the US, payment processing fees are generally deductible as an ordinary business expense. Track them from your processor statements or reports, since deposits arrive net of fees and gross sales should still be recorded. Confirm treatment with your accountant.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Payment acceptance and merchant economicsTopics: Card processing fees, Net settlement estimate, Blended effective rate
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine