Cash-on-cash return
What is cash-on-cash return?
Cash-on-cash return is the annual before-tax cash flow from a rental property divided by the total cash you invested, shown as a percentage. Unlike cap rate, it accounts for your mortgage, so it measures the return on your actual money in the deal. Real estate investors use cash-on-cash return to compare rental properties, decide how much to put down, evaluate BRRRR and value-add deals, and compare a rental's cash yield with other investments.
Cash-on-cash return
Annual cash flow ÷ cash invested × 100
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
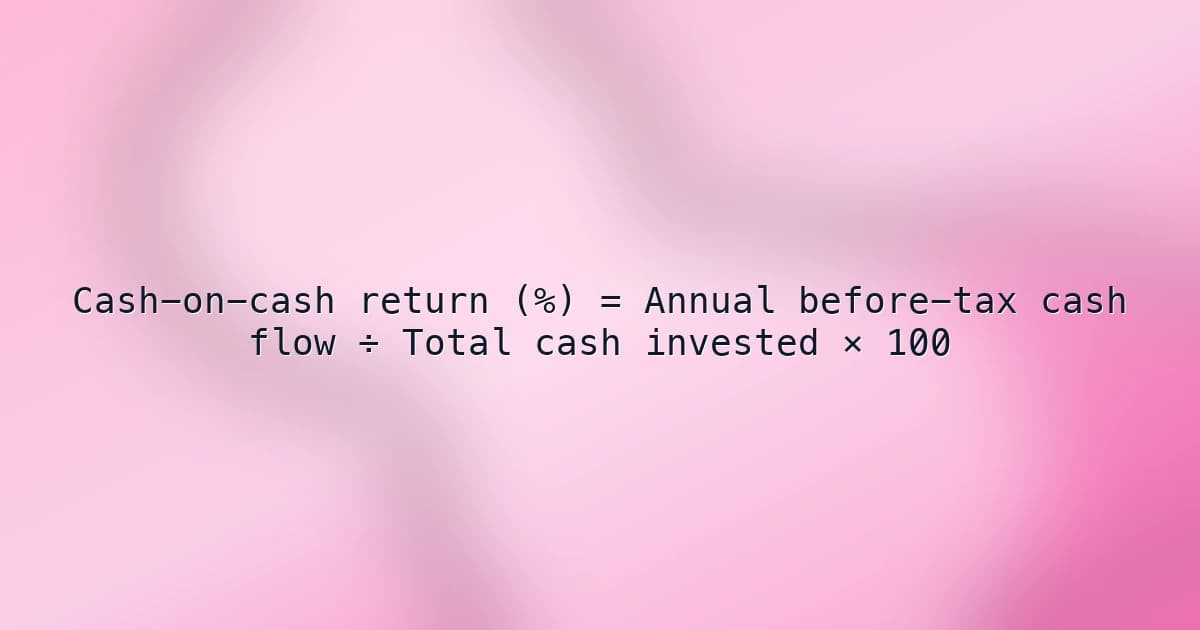
Cash-on-cash return formula
Divide annual before-tax cash flow by total cash invested and multiply by 100.
Cash-on-cash return (%) = Annual before-tax cash flow ÷ Total cash invested × 100- Annual before-tax cash flow = Rental income − Vacancy − Operating expenses − Mortgage payments (principal and interest) − Reserves.
- Total cash invested = Down payment + Closing costs + Upfront repairs + Initial reserves.
- Simple payback (years) = Total cash invested ÷ Annual cash flow.
Inputs explained
Use realistic first-year numbers, including vacancy and repair reserves, so the return reflects what will actually land in your bank account.
- Annual before-tax cash flow ($)
- Yearly cash left after rent collections, vacancy, operating expenses, reserves, and full mortgage payments, before income taxes. Don't add back principal paydown or depreciation.
- Total cash invested ($)
- All the cash you put in: down payment, buyer closing costs, loan fees, upfront repairs or renovations, and reserves required at purchase.
Example cash-on-cash return calculation
An investor buys a $300,000 duplex with 20% down ($60,000), $9,000 in closing costs, and $9,000 for repairs and reserves, a total of $78,000 invested. After all expenses and mortgage payments, the property produces $9,200 a year. Cash-on-cash return = $9,200 ÷ $78,000 × 100 ≈ 11.79%, and the simple payback is about 8.5 years.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the cash-on-cash return
- Input annual before-tax cash flow ($) from your rent roll minus mortgage payment (P&I), operating expenses, recurring capex reserve contribution, and vacancy assumptions consistent with your pro forma.
- Input total cash invested ($) as equity actually wired at closing—typically down payment, buyer-side closing costs, escrows, and immediate rehab capital if you capitalize it as initial equity.
- Read cash-on-cash (%) and cross-check the simple years-to-recover figure against your expected hold period and refinance timeline.
- Stress-test lower rent and higher vacancy before comparing CoC to unlevered yield metrics like cap rate or IRR models that include appreciation.
Common cash-on-cash return mistakes
- Leaving out vacancy, maintenance, capital expenditure reserves, or property management.
- Forgetting closing costs, loan fees, or upfront repairs in total cash invested.
- Adding principal paydown or appreciation into cash flow, which mixes cash-on-cash with total return.
- Comparing cash-on-cash return directly with cap rate, which ignores financing.
- Basing returns on optimistic rents instead of current market comps.
CoC and equity benchmarks
- Typical landlord CoC bands
- Published rental-investment education often cites roughly 8–12% cash-on-cash as a planning band for stabilized single-family rentals in normal markets, though leverage, rehab, and rents swing outcomes materially.
- Cash invested composition
- Underwriting usually treats cash-to-close as down payment plus closing costs and prepaid escrows; capital repairs belong inside cash invested only when funded at acquisition.
- Before-tax cash flow definition
- Classic CoC uses pretax cash available to equity after debt service; income taxes, depreciation timing, and refinance proceeds require parallel worksheets.
FAQs
Should I put 20% or 25% down to get a better cash-on-cash return?
A bigger down payment often lowers cash-on-cash return. On a $300,000 property at 7%, going from 20% to 25% down adds $15,000 of cash but saves only about $1,198 a year in mortgage payments. Cash flow rises to about $10,398, but cash-on-cash falls from 11.79% to about 11.18% on $93,000 invested. More down lowers risk and monthly payments, though.
How much cash flow do I need for a 10% cash-on-cash return?
Multiply your cash invested by your target. With $78,000 invested, you need $7,800 a year, or $650 a month, in before-tax cash flow for 10%. Alternatively, at $9,200 cash flow, you could invest up to $92,000 and still hit 10%.
How much does one vacant month hurt my cash-on-cash return?
If one unit renting for $1,400 sits empty for a month, cash flow falls from $9,200 to $7,800 and cash-on-cash drops from about 11.79% to 10%. Budget vacancy into your numbers, and keep a cash reserve so a vacancy doesn't force you to cover the mortgage from savings.
What happens to my return if I need a $5,000 repair in year one?
An unplanned $5,000 repair cuts first-year cash flow from $9,200 to $4,200, dropping cash-on-cash from 11.79% to about 5.38%. Inspect the property carefully before buying, budget for capital expenditures, and keep repair reserves separate from cash flow.
How much does a lower mortgage rate improve cash-on-cash return?
On a $240,000 loan, dropping from 7% to 6% lowers principal and interest from about $1,597 to $1,439 a month, saving about $1,894 a year. Cash flow rises to about $11,094, and cash-on-cash improves from 11.79% to about 14.22% with the same cash invested.
How does a BRRRR cash-out refinance change cash-on-cash return?
Pulling cash out lowers the cash left in the deal, which can sharply raise cash-on-cash return. If a refinance returns $50,000 of your $78,000 and higher payments cut cash flow to $5,500, cash-on-cash becomes about 19.64% on $28,000. But a bigger loan means more risk if rents fall or vacancy rises.
Is cash-on-cash return the same as total return on a rental property?
No. Total return also includes principal paydown and appreciation. In year one, a $240,000 loan at 7% pays down about $2,438 of principal, and 3% appreciation on a $300,000 property adds $9,000. With $9,200 in cash flow, that's about a 26.5% total return on $78,000, but only the cash flow is in your pocket.
How much would raising rent by $100 a unit improve my return?
On a duplex, $100 more per unit adds $2,400 a year in cash flow, taking it from $9,200 to $11,600. Cash-on-cash rises from about 11.79% to 14.87%. Check market rents and tenant turnover risk before increasing.
Is an 11.8% cash-on-cash return good?
Many rental investors aim for about 8–12% cash-on-cash for stabilized properties, though targets vary by market, risk, and expected appreciation. At 11.79%, $78,000 earns $9,200 a year, versus $3,900 at a 5% savings yield. Compare it with the risk, time, and effort of owning a rental.
What does a negative cash-on-cash return mean?
It means the property costs more each year than it brings in. A $1,200 annual shortfall on $78,000 invested is about −1.54%, so you'd be paying out of pocket to hold it. Some investors accept this in high-appreciation markets, but it adds risk. Consider raising rents, cutting expenses, or putting more down.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Residential rental investment returnsTopics: Cash-on-cash return, Levered rental yield, Equity invested
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine