Years to double (compound growth)
What is an investment doubling time calculator?
An investment doubling time calculator shows how many years it takes money to double at a steady annual compound return. It gives the exact answer using logarithms and the quick Rule of 72 estimate side by side, so you can see how close the shortcut is. Investors, retirement savers, financial advisors, and students use it to compare stocks, bonds, savings accounts, and CDs, understand compound interest, and see how fast debt grows at a given interest rate.
Years to double (compound growth)
Exact continuous-compounding style estimate via ln
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
Doubling time formula and the Rule of 72
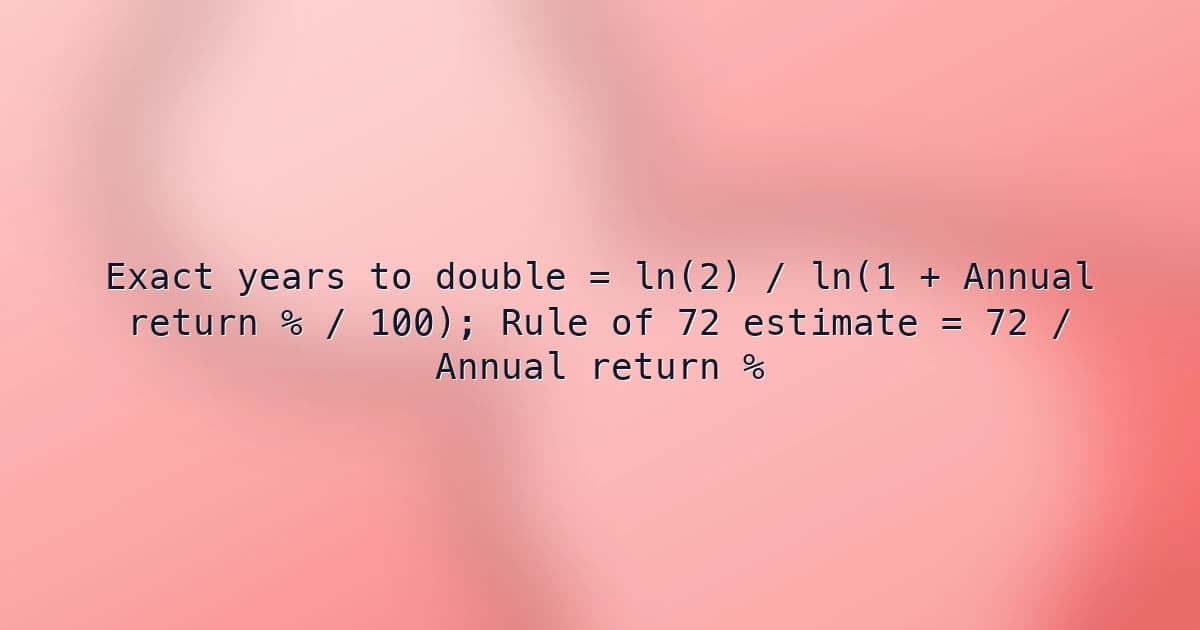
With annual compounding, money doubles when (1 + r) raised to the number of years equals 2. Solving for years gives the exact logarithmic formula. The Rule of 72 approximates that answer by dividing 72 by the percentage return.
Exact years to double = ln(2) / ln(1 + Annual return % / 100); Rule of 72 estimate = 72 / Annual return %- To find the return needed to double in a set number of years: required return = 2^(1 / years) - 1.
- The Rule of 72 is most accurate between roughly 6% and 10%; the Rule of 70 or 69.3 fits low rates and continuous compounding better.
- Tripling time = ln(3) / ln(1 + r); quadrupling takes two doubling periods, and eight times takes three.
Inputs explained
The result depends entirely on one assumption, so choose a return that reflects long-run compound performance after the costs you actually pay.
- Average annual return (%)
- The annualized compound return you expect over the full holding period, sometimes called CAGR. Use a long-run assumption rather than last year's performance, subtract fund fees and advisory costs, and consider taxes if the account is taxable. To see how long purchasing power takes to double, use the real return after inflation instead of the nominal return.
Example doubling time calculation
At a 7% average annual return, exact doubling time is ln(2) / ln(1.07), about 10.24 years, while the Rule of 72 estimates 72 / 7, about 10.29 years. Over 30 years, that is roughly 2.93 doublings, so $10,000 would grow to about $76,123. At 6%, perhaps after a 1% annual fee, doubling slows to about 11.90 years.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the years to double (compound growth)
- Input average annual return (%) using the long-run assumption you are modeling, not a single-year performance outlier.
- Review the exact logarithmic years-to-double output for the primary estimate under constant compounding assumptions.
- Compare the Rule of 72 shortcut output to the exact value to sanity-check intuition and communicate estimates quickly.
- Run multiple return scenarios to understand how conservative versus optimistic assumptions shift your projected doubling timeline.
Common doubling time mistakes
- Using the simple average of yearly returns instead of the compound annual growth rate, which overstates growth when returns are volatile.
- Ignoring fund expense ratios, advisory fees, and tax drag, which can add years to every doubling period.
- Treating nominal doubling as doubling of purchasing power without adjusting for inflation.
- Applying doubling time to a portfolio receiving regular contributions or withdrawals, which changes the timeline.
- Relying on the Rule of 72 at very low or very high rates where its error grows.
- Assuming a high recent return will continue for decades and planning around a best-case doubling time.
Compounding and doubling-time context
- Rule of 72 as a mental shortcut
- The Rule of 72 is a widely used approximation for quick estimates, while logarithmic formulas provide more precise doubling-time results.
- Return assumption sensitivity
- Small differences in annual return assumptions can materially change doubling timelines over multi-decade horizons.
- Nominal return vs real purchasing-power growth
- A nominal doubling timeline does not account for inflation; real wealth doubling can take longer when price levels rise.
FAQs
My portfolio averaged 10% a year but has not doubled in over seven years—why?
A simple average of yearly returns overstates compound growth when returns swing up and down. A rough rule is that compound return is about the average return minus half the variance, so a 10% average with 20% volatility compounds closer to 8%, which doubles in about 9.0 years instead of 7.3. Fees, taxes, withdrawals, and cash drag also slow growth. Use your actual annualized return (CAGR) from your brokerage statement in this calculator.
What annual return do I need to double my money in 5 years?
Required return = 2^(1 / years) - 1. Doubling in 5 years needs about 14.87% a year; doubling in 10 years needs about 7.18%. Sustaining nearly 15% for five straight years is well above what diversified portfolios have historically averaged, so a 5-year doubling plan usually implies concentrated, high-risk investments.
Someone promised to double my money in two years—is that realistic?
Doubling in two years requires about 41.4% a year, and doubling in one year requires 100%. Guaranteed returns at that level are a classic warning sign of fraud, including Ponzi schemes and fake crypto or forex platforms. Legitimate investments with that upside carry a real chance of large losses and never guarantee the result.
How much do investment fees slow down how fast my money doubles?
Subtract fees from the return before calculating. A 7% portfolio doubles in about 10.24 years, but with a 1% annual fee it earns 6% and doubles in about 11.90 years, and at 2% in fees it takes about 14.21 years. Over 30 years, a 1% fee costs about 0.4 of a doubling and a 2% fee about 0.8, which on $10,000 is the difference between roughly $76,000 and $57,000 or $43,000.
How long does it take to double my purchasing power after inflation?
Use the real return: (1 + nominal return) / (1 + inflation) - 1. A 7% return with 3% inflation is about a 3.88% real return, which doubles purchasing power in about 18.2 years, not 10.24. The nominal balance still doubles in about 10 years, but it buys much less than twice as much.
How long until my money doubles in a high-yield savings account or CD?
At 4.5% interest, money doubles in about 15.7 years in nominal terms. After 3% inflation the real return is only about 1.46%, so purchasing power would take roughly 48 years to double, and taxes on interest stretch that further. Savings accounts and CDs work well for safety and short-term goals, but long-term growth usually needs higher-return assets.
How fast does credit card debt double if I do not pay it down?
At 24% APR, a balance roughly doubles in about 3.22 years with annual compounding and about 2.92 years with monthly compounding, which is how most cards charge. Paying only the minimum can leave a balance growing or barely shrinking, so prioritize paying off high-interest debt before chasing investment returns.
Should I use the Rule of 72, 70, or 69 for my estimate?
The Rule of 72 works best for returns around 6% to 10%. At 2%, it says 36 years while the exact answer is 35.0, so the Rule of 70 fits low rates better. At 18%, it says 4 years versus an exact 4.19. The Rule of 69.3 matches continuous compounding. For decisions, use the exact result from this calculator.
How many times will my money double before I retire?
Divide your years until retirement by the doubling time. At 7% over 30 years, money doubles about 2.93 times, so $10,000 invested today grows to about $76,123. Starting 10 years earlier adds roughly one more doubling, which is why early investing has such a large effect on retirement balances.
I add money every month—does doubling time still apply to my account?
Doubling time describes a single lump sum growing with no deposits or withdrawals. Regular contributions make the total balance grow faster than doubling time suggests, because new deposits add to growth. Use doubling time to understand each dollar's growth rate, and a compound savings calculator to project a balance with monthly contributions.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Investing education & compounding analysisTopics: Doubling time, Rule of 72, Compound return planning
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine