Max monthly housing payment (PI)
What is a maximum housing payment calculator?
A maximum housing payment calculator estimates the largest monthly mortgage payment you could qualify for based on your gross income, existing monthly debts, and a lender's debt-to-income (DTI) limit. Home buyers use it before getting pre-approved to understand how much house they can afford, and loan officers and real estate agents use it to set realistic price ranges. It shows how car loans, student loans, and credit card payments reduce the mortgage payment a lender will allow.
Max monthly housing payment (PI)
Income × DTI cap − non-housing debts
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
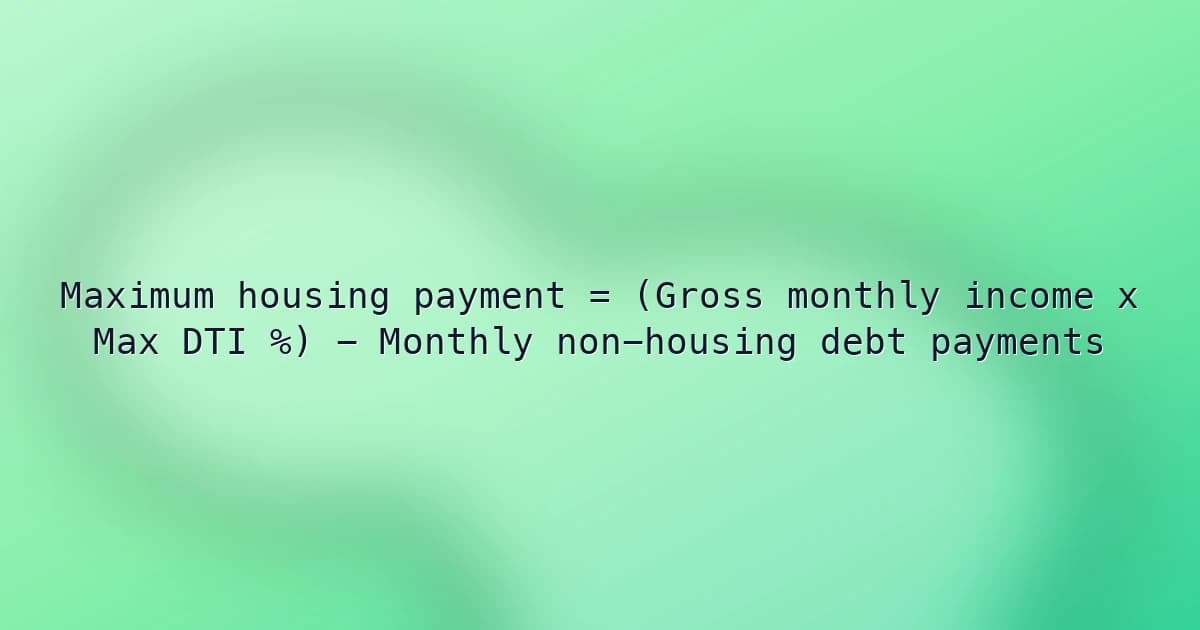
Maximum housing payment formula
Multiply gross monthly income by the maximum DTI ratio to get total allowed monthly debt, then subtract existing non-housing debt payments. What remains is the room for your housing payment. Lenders count the full housing payment, including property taxes, homeowners insurance, HOA dues, and mortgage insurance, so subtract those to find the amount left for principal and interest.
Maximum housing payment = (Gross monthly income x Max DTI %) - Monthly non-housing debt payments- Principal and interest budget = Maximum housing payment - Property taxes - Homeowners insurance - HOA dues - Mortgage insurance.
- Front-end ratio check = Housing payment / Gross monthly income; the classic 28/36 rule caps housing at 28% and total debt at 36%.
- Loan amount from a P&I budget depends on rate and term; at 6.5% over 30 years, each $1,000 of monthly P&I supports roughly $158,000 of loan.
Inputs explained
Enter income and debts the way a lender will count them, from pay stubs, tax returns, and your credit report, not take-home pay or estimates.
- Gross monthly income ($)
- Pre-tax monthly income for everyone on the loan: salary, plus bonus, overtime, commission, self-employment, or rental income that a lender can document, usually with a two-year history. Self-employed borrowers are typically qualified on net income after business deductions from tax returns, not gross revenue.
- Monthly debt payments ex-housing ($)
- Minimum monthly payments on your credit report: car loans and leases, student loans, credit cards, personal loans, plus child support or alimony. Exclude utilities, phone bills, insurance, and groceries, which lenders do not count as debt.
- Max total debt-to-income (%)
- The highest back-end DTI the loan program allows. 43% is a common planning benchmark, while conventional, FHA, and VA loans may approve higher ratios with strong credit, savings, or automated underwriting approval. Lower caps such as 36% give a more conservative budget.
Example maximum housing payment calculation
A borrower earns $9,200 a month before taxes and pays $680 a month in other debts. At a 43% DTI limit, total allowed debt is $3,956, leaving $3,276 for the housing payment. If property taxes are $450, insurance $150, and mortgage insurance $120 a month, about $2,556 remains for principal and interest, which supports a loan of roughly $404,000 at 6.5% over 30 years, or a home price near $449,000 with 10% down.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the max monthly housing payment (pi)
- Input gross monthly income ($) using verifiable pre-tax household income considered in your lending scenario.
- Enter monthly debt payments ex-housing ($) including recurring minimum obligations such as auto, student, credit-card, and personal-loan payments.
- Set max total debt-to-income (%) to the underwriting cap you want to test for your loan profile.
- Review approximate max for P&I and total debt capacity, then reserve budget for taxes, insurance, HOA, and mortgage insurance before setting a home-price target.
Common housing affordability mistakes
- Treating the result as principal and interest only when lenders count taxes, insurance, HOA, and mortgage insurance in the same DTI limit.
- Using take-home pay instead of gross income, or gross revenue instead of net self-employment income.
- Leaving out credit card minimums, car leases, child support, or deferred student loans that lenders still count.
- Counting new bonus, overtime, or side income without the history most lenders require.
- Assuming the lender's maximum is comfortable for your actual monthly budget.
- Opening new credit or financing a car before closing, which raises DTI and can derail approval.
- Forgetting that higher interest rates shrink the loan amount the same payment can support.
DTI-based housing affordability context
- Front-end vs back-end qualification framing
- Lenders often evaluate both housing-only and total-debt ratios, so a single DTI cap should be treated as directional until full underwriting.
- Credit and reserve overlays
- Program limits can tighten or loosen effective DTI tolerance based on credit score, reserves, loan type, and occupancy profile.
- PI-only vs full housing payment
- Principal and interest capacity can materially overstate all-in affordability if property taxes, insurance, HOA dues, or PMI are not separately budgeted.
FAQs
Is this number my whole mortgage payment or just principal and interest?
Lenders apply the DTI limit to your full housing payment: principal, interest, property taxes, homeowners insurance, HOA dues, and mortgage insurance. So treat the result as your total housing budget. With $3,276 available and $720 a month in taxes, insurance, and mortgage insurance, about $2,556 is left for principal and interest. Get local tax and insurance quotes before converting the result into a loan amount.
How do I turn my maximum payment into a home price I can afford?
Subtract taxes, insurance, HOA, and mortgage insurance to get your principal and interest budget, then convert it to a loan amount using your expected rate and term. At 6.5% over 30 years, a $2,556 principal and interest payment supports about $404,000 in loan; with 10% down, that is a price around $449,000. Each 1% rise in rates cuts the loan amount by roughly 10%, so recheck when rates move.
The lender says I qualify for more than I feel comfortable paying—which number should I use?
Use the lower one. DTI limits are based on gross income and ignore taxes withheld, retirement savings, childcare, and other costs. A $3,276 housing payment is 43% of $9,200 gross income but about 47.5% of $6,900 in take-home pay. Build a monthly budget from take-home pay, keep an emergency fund, and choose a payment that leaves room for repairs and savings.
Should I pay off my car loan or credit cards before applying for a mortgage?
It can significantly increase what you qualify for. Every dollar of monthly debt removed adds a dollar of housing capacity; paying off a $400-a-month car loan could support roughly $63,000 more in mortgage at 6.5% over 30 years. Compare that to keeping the cash for your down payment and reserves, and ask your loan officer before paying off accounts, since timing and credit score effects matter.
My student loans are on an income-driven plan or in deferment—what payment do lenders count?
It depends on the loan program. Some programs accept your documented income-driven payment, even a low one, while others count a percentage of the outstanding balance, commonly around 0.5% to 1% a month, when the payment is zero or deferred. On a $60,000 balance, that could mean $300 to $600 a month in DTI. Ask lenders which rule applies to your loan type.
I am self-employed or a 1099 contractor—what income will lenders use for my DTI?
Lenders usually average net income from your last two years of tax returns, after business deductions, not gross revenue or bank deposits. Large write-offs lower qualifying income, and declining income year over year can lower it further. Enter net monthly income from your returns in this calculator, or ask about bank statement loans if your tax returns understate cash flow.
What is the difference between front-end and back-end DTI, and which one limits me?
Front-end DTI is housing payment divided by gross income; back-end DTI includes all debts. Under the traditional 28/36 guideline, $9,200 in income allows $2,576 for housing on the front end and $3,312 in total debt on the back end. Many loan programs focus mainly on back-end DTI, but if you have few debts, a front-end limit may be the tighter constraint.
What maximum DTI will my lender actually allow?
It varies by loan type and borrower strength. 43% is a widely used benchmark, but conventional loans approved through automated underwriting can go higher, and FHA and VA loans may allow higher ratios with strong credit, cash reserves, or other compensating factors. Run this calculator at 36%, 43%, and 50% to see a conservative, typical, and stretch range before talking with lenders.
If I add my spouse or partner to the loan, will I qualify for a bigger payment?
Usually, but their debts count too. Adding $4,000 in monthly income and $500 in debts to the example raises income to $13,200 and debts to $1,180, increasing the maximum housing payment from $3,276 to about $4,496 at 43% DTI. If a co-borrower has high debts or low credit scores, compare scenarios with and without them, since credit can affect the rate.
Can bonus, overtime, side-gig, or rental income count toward my mortgage qualification?
Often, if it is documented and stable. Lenders typically want about a two-year history for bonus, overtime, commission, and self-employment income, and may average it. For rental income, many lenders count only a portion of rent, often around 75%, to allow for vacancy and expenses. Enter only income you can document to avoid overestimating your budget.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Mortgage affordability & pre-qualification planningTopics: Debt-to-income ratio, Housing payment capacity, Mortgage prequalification
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine