Student loan monthly payment
What is a student loan payment calculator?
A student loan payment calculator estimates your fixed monthly payment based on your loan balance, interest rate, and repayment term. It uses standard amortization, so each payment covers interest first and the rest reduces your balance until the loan is paid off. Students, graduates, and parents use it to plan budgets, compare 10-year and longer repayment terms, check whether refinancing makes sense, and see how extra payments shorten payoff.
Student loan monthly payment
Standard fixed-rate payoff schedule
Embed this free calculator on your website—copy the snippet after signup and keep the Built with Calclet link for attribution (or upgrade to remove branding).
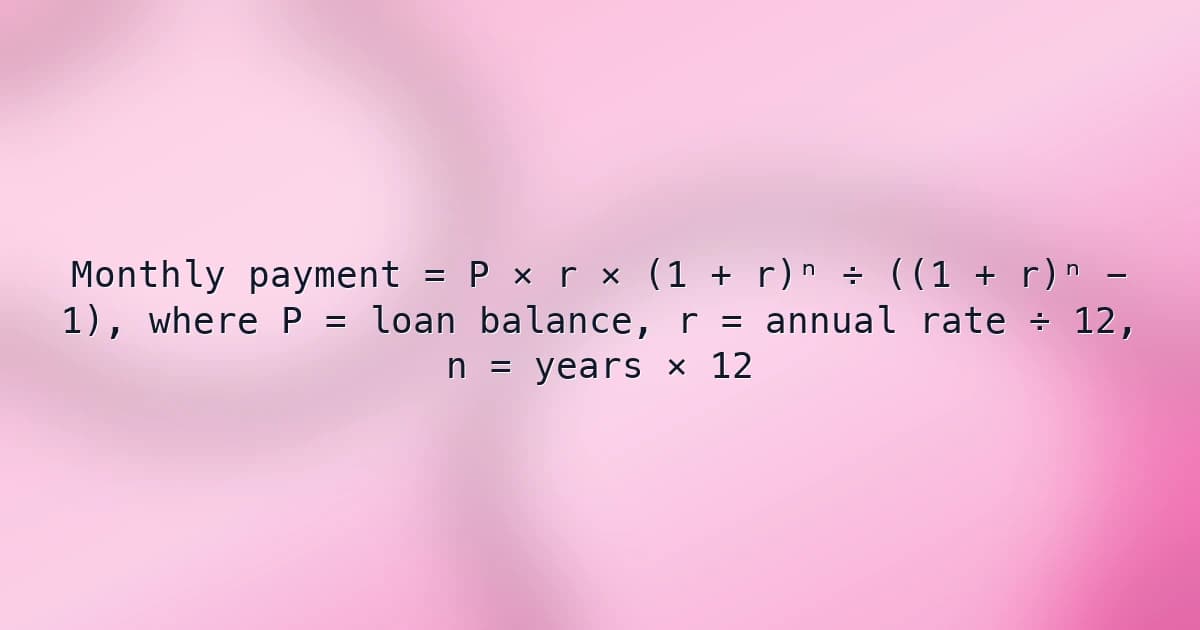
Student loan payment formula
The standard amortization formula spreads principal and interest evenly across every monthly payment.
Monthly payment = P × r × (1 + r)ⁿ ÷ ((1 + r)ⁿ − 1), where P = loan balance, r = annual rate ÷ 12, n = years × 12- Total interest = Monthly payment × Number of payments − Loan balance.
- Longer terms lower the monthly payment but increase total interest paid.
- Income-driven repayment plans calculate payments from income instead, so they won't match this standard payment.
Inputs explained
Use the current balance and rate from your loan servicer's website or statement.
- Loan balance ($)
- Current amount owed, including any unpaid interest that has been added to the balance.
- Annual interest rate (%)
- Fixed interest rate on the loan. For several loans, run each one separately or use a weighted average rate.
- Repayment term (years)
- Number of years until the loan is paid off. Standard repayment for federal loans is commonly 10 years.
Example student loan payment calculation
A graduate owes $38,500 at 6.8% interest on a 10-year plan. The monthly payment is about $443.06. Over 120 payments, they'll pay about $53,167 in total, including about $14,667 in interest. Stretching the term to 20 years lowers the payment to about $293.89 but more than doubles total interest to about $32,033.
Put this calculator on your site
We'll copy this tool into your Calclet account—tweak branding and fields, then paste the embed on WordPress, Webflow, Shopify, or any HTML page. Every embed can link back to Calclet for discovery.
How to use the student loan monthly payment
- Pull current principal balance from your servicer dashboard or NSLDS export—use post-capitalization figures if you just exited grace or deferment.
- Input the note’s fixed annual interest rate exactly as stated on the Truth-in-Lending-style disclosure (APR), not a blended average across multiple loans unless you already consolidated.
- Set repayment term in whole years to mirror your scheduled payoff window for standard fixed amortization (not IDR recert months).
- Compare the estimated monthly payment against autopay drafts and stress-test +$50 or biweekly half-payments if you model accelerated payoff elsewhere.
Common student loan payment mistakes
- Using the original loan amount instead of the current balance with added interest.
- Choosing the longest term for a lower payment without checking total interest.
- Refinancing federal loans without weighing the loss of federal repayment protections.
- Making extra payments without asking the servicer to apply them to principal.
- Averaging rates across loans instead of weighting by balance.
Student loan repayment context
- Standard repayment shape
- Federal loan servicers label fully amortizing, equal installments over a stated term as Standard repayment—often quoted at ten years when eligible, distinct from graduated or income-driven plans.
- APR versus simple interest
- Promissory notes express annual interest; amortization engines convert to a periodic rate (APR/12 here) so early payments skew toward interest until the balance declines.
- Grace and capitalization
- Unsubsidized loans may accrue in school; unpaid interest can capitalize at status changes—raise principal before modeling if your servicer already folded accrued interest into balance.
FAQs
How much faster will I pay off my student loans with an extra $100 a month?
On $38,500 at 6.8%, raising the payment from $443.06 to $543.06 pays the loan off in about 91 months, roughly 7 years and 7 months instead of 10 years. Total interest falls from about $14,667 to about $10,872, saving roughly $3,795. Ask your servicer to apply the extra amount to principal.
Should I choose a 10-year or 20-year student loan repayment term?
It's a trade-off between monthly cash flow and total cost. On $38,500 at 6.8%, a 10-year term costs $443.06 a month and about $14,667 in interest. A 20-year term drops the payment to about $293.89 but raises interest to about $32,033. If you choose the longer term, you can still pay extra when you can afford it.
How much would I save by refinancing my student loans to a lower rate?
Refinancing $38,500 from 6.8% to 5% over 10 years lowers the payment from $443.06 to about $408.35 and saves about $4,165 in interest. Refinancing federal loans with a private lender ends access to federal benefits such as income-driven repayment and forgiveness programs, so weigh those before switching.
What monthly payment do I need to pay off my student loans in 5 years?
Set the term to 5 years. $38,500 at 6.8% needs about $758.72 a month, about $316 more than the 10-year payment. Total interest drops from about $14,667 to about $7,023.
How does capitalized interest change my student loan payment?
Unpaid interest added to your balance raises the payment and the total interest. If $2,600 of interest built up during school or deferment is added to $38,500, the new $41,100 balance costs about $472.98 a month over 10 years, about $30 more, and interest rises to about $15,658.
Should I put a $5,000 lump sum toward my student loans?
If you keep paying $443.06 a month after putting $5,000 toward a $38,500 loan at 6.8%, the loan is paid off in about 100 months instead of 120, saving about $4,304 in interest. Make sure you have an emergency fund first, and compare with paying off higher-rate debt.
Do biweekly student loan payments save money?
They can, because 26 half-payments a year equal 13 monthly payments. Paying $221.53 every two weeks on $38,500 at 6.8% pays the loan off in about 9 years and saves about $1,760 in interest, if your servicer applies each payment when it arrives. Many servicers hold partial payments until the full amount is due, so check first.
How do I calculate payments on multiple student loans with different rates?
Run each loan separately and add the payments. $20,000 at 5.5% and $18,500 at 7.05% over 10 years cost about $217.05 and $215.28, or $432.33 a month in total. The balance-weighted average rate is about 6.24%. Federal Direct Consolidation uses that weighted average rounded up to the nearest one-eighth of a percent, here 6.25%.
How much student loan debt can I afford on my salary?
One common guideline keeps student loan payments around 10% of gross monthly income. On a $55,000 salary, that's about $458 a month, which supports a balance of about $39,800 at 6.8% over 10 years. Your own budget, other debts, and living costs matter more than any rule of thumb.
How much interest builds up during deferment or forbearance?
Multiply the balance by the annual rate and divide by 12. $38,500 at 6.8% builds about $218 of interest a month, or about $1,309 over six months, on loans where interest isn't covered. If that interest is added to your balance, future payments and total interest go up.
Related calculators
Related guides
Step-by-step articles on building, embedding, and ranking calculator pages like this one.
Category: Education debt repaymentTopics: Level amortization, Annual percentage rate, Standard repayment term
Last reviewed: 2026-05-07
Reviewed by: Souhayb Kama Ldine